
Shelburne County · Yarmouth
Mortgage broker serving Shelburne, Nova Scotia
Shelburne is the Loyalist town on a large sheltered harbour on the South Shore, settled in 1783. Its waterfront streets are among the oldest in the province, its incomes come from the fishery, boat repair and public services, and prices are low enough that buyers from away take notice. Insurance on an old house is the first hurdle.
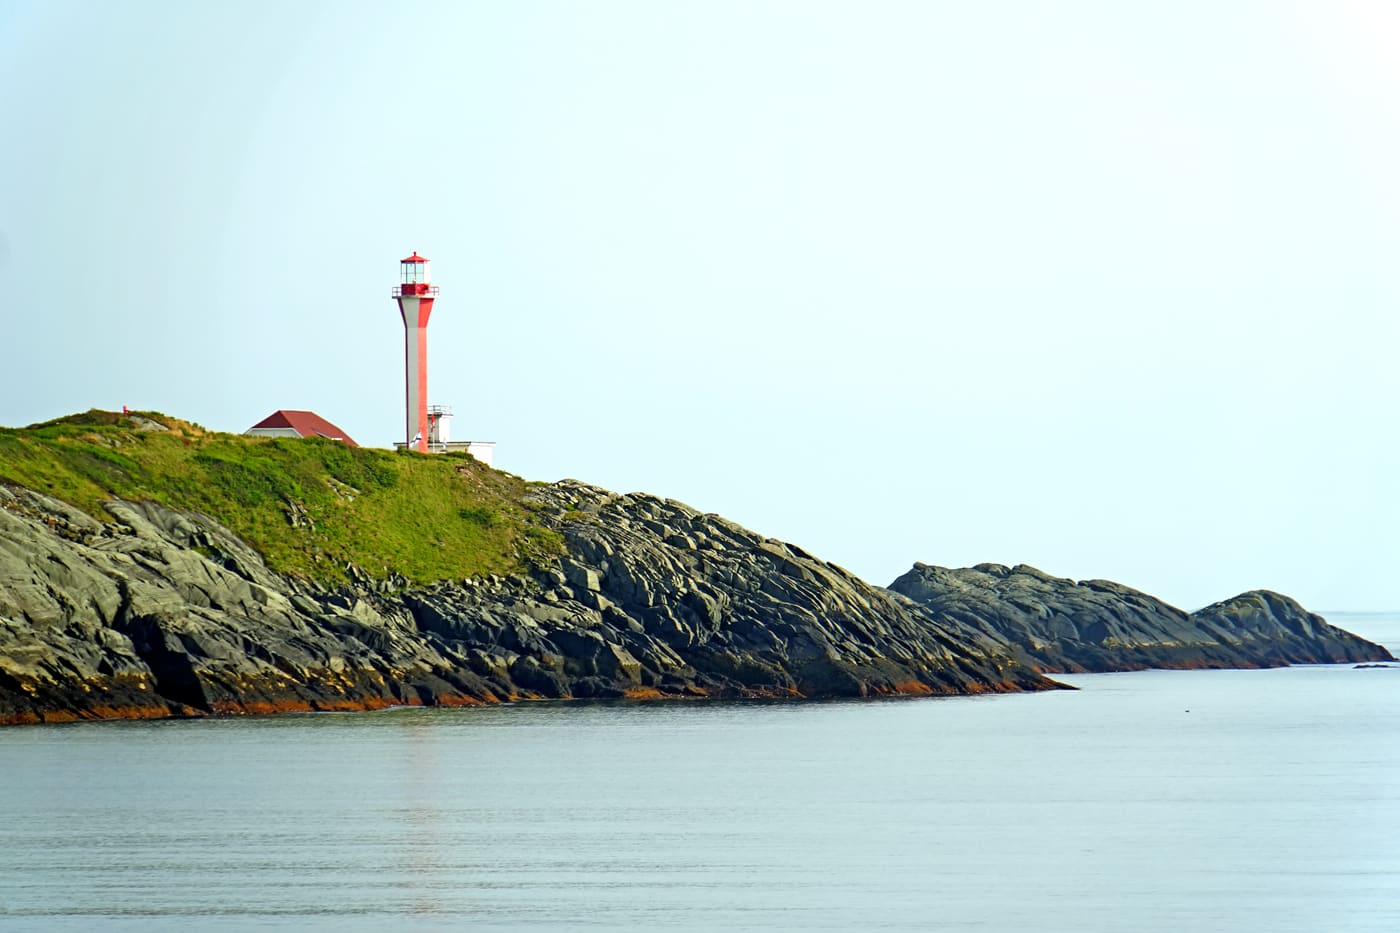
Cape Forchu, Yarmouth
What does it cost to buy a home in Shelburne?
Shelburne is in Shelburne County, in the Yarmouth housing region. On the August 2026 Yarmouth average of $313,944: minimum down payment $15,697, Town of Shelburne deed transfer tax $4,709 at 1.5%, and roughly $21,906 cash to close with legal costs. The $310,177 mortgage, premium included, needs household income near $69,539 at the stress-test floor.
Looking for a mortgage broker, mortgage agent or mortgage advisor in Shelburne? In Nova Scotia that is one licensed role, and the licence covers the whole province.
The tax in Shelburne
Town of Shelburne charges 1.5% deed transfer tax, paid at closing. It follows the property: Municipality of the District of Shelburne 1.5%, Municipality of the District of Barrington 1.5%, Region of Queens Municipality 1.5%. Every municipality’s rate →
- Minimum down payment $15,697
- Town of Shelburne deed transfer tax $4,709
- Legal, recording and title $1,500
Assumptions: 5%/10% minimum down payment, CMHC premium financed into the mortgage, 25-year amortization, qualifying at the 5.25% stress-test floor (or the contract rate plus 2% if higher), property tax about 1% of price, heat $150/month, GDS 39%. Legal $1,000, recording $200 and title insurance $300 are typical Nova Scotia figures, not quotes.
Which program fits here
The First-time Homebuyers Program (2–4% down, credit unions only) caps at $500,000 here; the Down Payment Assistance Program at $375,000. The $313,944 average sits under both, so a typical Shelburne first-time buyer can fit either. Above $200,000 income or below 630 credit, neither fits; a standard insured mortgage with 5% down does.
Refinancing or renewing a mortgage in Shelburne
Already own in Shelburne? Mortgage refinancing can go to 80% of the home’s appraised value: $251,155 on the Yarmouth average of $313,944. No deed transfer tax applies when the owner stays the same. At renewal, send the lender’s offer before you sign it and I will check it against other lenders.
Go deeper
The detail, if you want it
The arithmetic on the Yarmouth average
| Purchase price | $313,944 |
| Minimum down payment | $15,697 |
| CMHC premium (4%, financed) | $11,930 |
| Mortgage amount | $310,177 |
| Town of Shelburne deed transfer tax (1.5%) | $4,709 |
| Legal, recording and title (typical) | $1,500 |
| Cash to close | $21,906 |
| Monthly payment at 4.45% (chartered-bank prime rate, Bank of Canada, 2026-09-30), 25 years | $1,708 |
| Each quarter-point of rate on this mortgage | $43 a month |
| Monthly payment at the 5.25% qualifying rate (what you must qualify at, not what you pay) | $1,848 |
| Income needed to qualify | $69,539 |
Run it on a specific price → · Payment at your own rate →
Worked start to finish: Yarmouth first-time buyer: 5% DPAP loan and 1% deed tax (illustrative examples on this region’s figures).
What lenders ask about Shelburne homes
- The historic waterfront district holds eighteenth and nineteenth-century houses. The insurer asks about wiring, heating and the roof before the lender asks anything, and no insurance binder means no funding.
- Outside the town, in the District of Shelburne, homes are on well and septic. Lenders want a potability test and septic evidence.
- Shore properties may be seasonal. Without year-round road access and permanent heat a property finances as recreational, with more down and fewer lenders.
Income and closing in Shelburne
- Lobster fishing income is seasonal and often self-employed. Lenders average two years of Notices of Assessment, and some count consistent off-season Employment Insurance.
- The hospital, the schools, the town and marine trades supply salaried and hourly income that qualifies on a letter of employment.
- Retirees and buyers from other provinces qualify on pension and investment income, or on remote employment the employer confirms in writing.
- The Town of Shelburne charges 1.5% deed transfer tax: $4,709 on the Yarmouth region average. The District of Shelburne and the District of Barrington also charge 1.5%.
- Shelburne County is grouped with the South Shore for the Down Payment Assistance Program, at a $375,000 cap. The First-time Homebuyers Program cap is $500,000.
- Application, documents and signing are remote, and you choose your own Shelburne lawyer. Sales are few, so allow extra time for the appraisal.
Comparing mortgage brokers in Shelburne
Nova Scotia licenses brokers for the whole province and ranks none of them, so check the licence, the number of lenders and any fee in writing. The four checks → · Broker, agent, advisor or specialist? →
Why a broker
Licensed, independent, paid by the lender
- Licensed in Nova Scotia Associate broker 3001134, verifiable on the provincial register
- $0 broker fee On a standard residential mortgage the lender pays, not you
- Banks, credit unions, monolines One application, one credit check, placed with the lender that reads your file best
- Every part of the province Bedford office, remote process: Yarmouth to Sydney, the same four steps
Questions people ask
What is the deed transfer tax in Shelburne?
The Town of Shelburne charges 1.5% of the purchase price, and so does the Municipality of the District of Shelburne around it. On a $250,000 purchase that is $3,750, paid in cash on closing.
Can I get a mortgage on a very old house in Shelburne?
Usually the lender will; the insurer decides. Insurers look closely at wiring, heating, plumbing and the roof on an old house, and the lender requires an insurance binder before funding. Get the insurance quote early in the condition period.
How do lenders treat lobster income in Shelburne?
As seasonal or self-employed income, averaged over two years of Notices of Assessment. Two steady years qualify with mainstream lenders. A first year, or one strong year after a weak one, usually needs an alternative lender until another return is filed.
Do I need to come to Bedford to get a mortgage in Shelburne?
No. Nothing in the file needs you there: application, uploads and signing are remote, an appraiser covering Shelburne County does the appraisal, and you choose your own Shelburne lawyer.
Still unsure? Ask me directly.
If your question isn't here, your situation is probably specific. Fifteen minutes on the phone beats reading another page, and nothing is pulled on your credit.
(902) 298-0218 · Monday to Friday, 8:00 am to 10:00 pm Atlantic
Buying, building or renewing in Shelburne?
Send the listing or your renewal statement. You get back the Shelburne tax, the cash to close, which program you fit and what the file needs — within a business day, at no fee.
(902) 298-0218 · Monday to Friday, 8:00 am to 10:00 pm Atlantic