

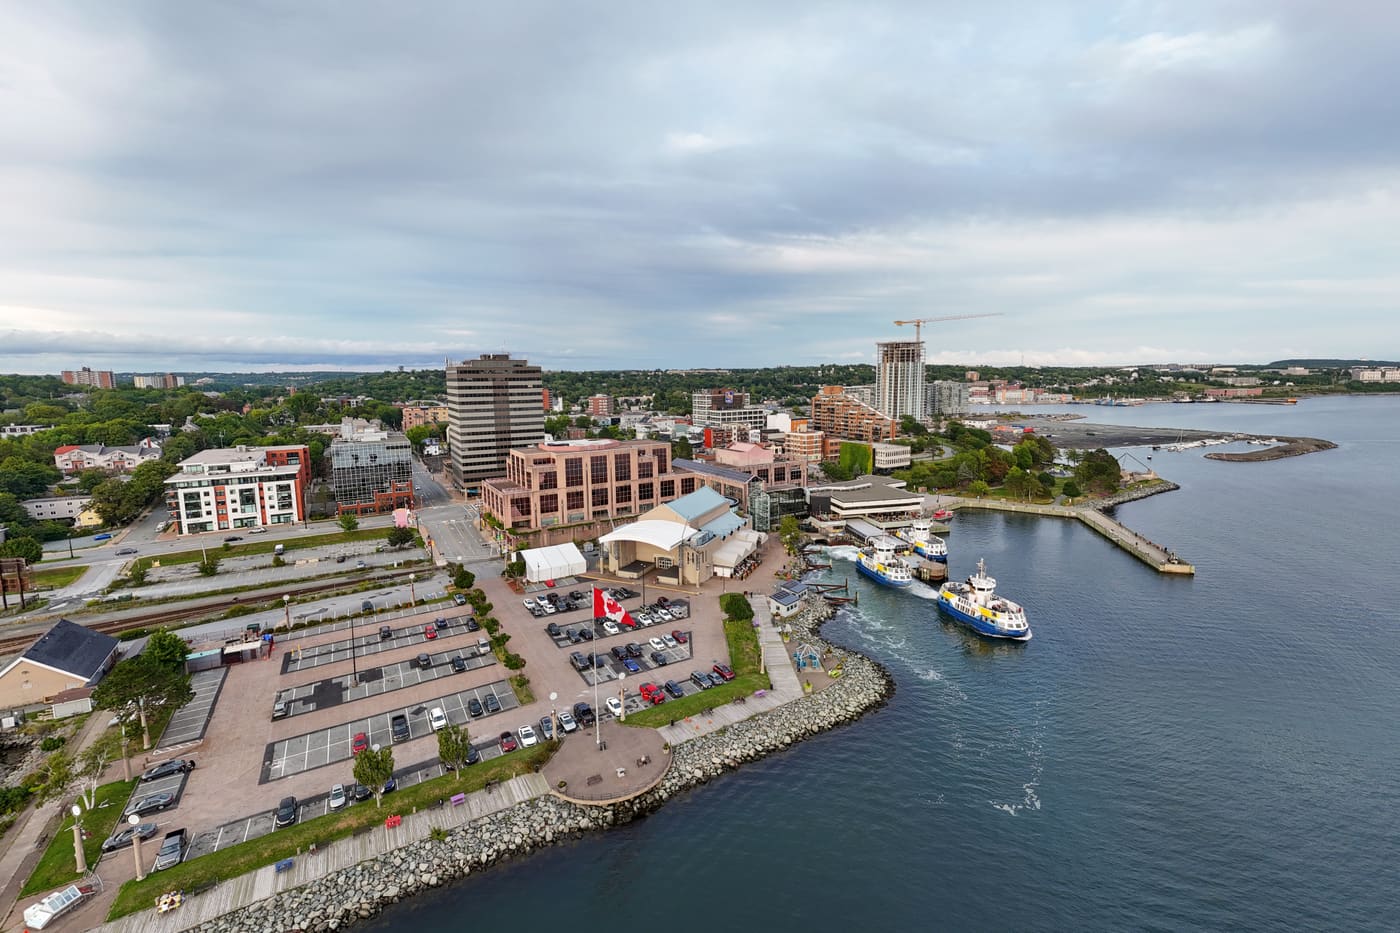
Dartmouth
Mortgages for CAF members posted to Nova Scotia
CFB Halifax, 12 Wing Shearwater and 14 Wing Greenwood give you about a week to find a house, so the mortgage work should be finished before you land.
What should a CAF member do about a mortgage before a posting to Nova Scotia?
Get a pre-approval before the house hunting trip. The relocation directive allows up to 5 days and 5 nights at the new location, normally no more than 7 days including travel: too short to arrange financing from scratch. A pre-approval takes one to three business days once documents are in, holds a rate, and makes your offer compete.
The order that works
The common mistake is arriving on the house hunting trip with a realtor booked and no financing. The trip is taken after official notification of posting and normally before the change of station date; a member takes either a house hunting trip or a destination inspection trip, not both: a one-shot window.
The posting order: finance first, then fly
- Done remotely, from your current base (steps 1–3)
- The one-shot window (step 4)
- Posting message received Start the pre-approval remotely from your current base.
- Send Riley the date Confirm the supported price and the cash to close. If you own now, ask about porting before the sale, not after.
- Pre-approval 1–3 business days Rate held 90–120 days, depending on the lender.
- House hunting trip 5 days, 5 nights Offers with a short financing condition, backed by the letter.
- Offer accepted 5–10 business days to close Appraisal, commitment, insurance binder, lawyer.
- Keys Deed and mortgage registered by your local lawyer.
- Halifax-Dartmouth average $592,675, deed transfer tax $8,890
- Annapolis Valley average $394,019, deed transfer tax $5,910
Trip length from the Canadian Armed Forces Relocation Directive (CAFRD); approval timings are typical Nova Scotia business days. August 2026 regional averages from Nova Scotia Association of REALTORS® / CREA monthly statistics; deed transfer tax at the HRM and Kings County rates. Last verified September 20, 2026.
The pre-approval is the slow part: income documents, pay statement, credit and down payment verification. Deed transfer tax alone is 1.5% in HRM and cannot be financed (closing cost calculator). On the trip, send each listing the evening you view it and get the property-specific answer overnight. The approval timeline in detail →
Go deeper
The detail, if you want it
Where you will be buying
| Posting | Where people buy | Regional average | Deed transfer tax | Provincial program cap |
|---|---|---|---|---|
| CFB Halifax / the dockyard | Halifax, Bedford, Sackville | $592,675 | 1.5% — $8,890 | $570,000 |
| 12 Wing Shearwater | Dartmouth, Eastern Passage, Cole Harbour | $592,675 | 1.5% — $8,890 | $570,000 |
| 14 Wing Greenwood | Kentville, New Minas, Berwick, Middleton | $394,019 | 1.5% — $5,910 | $500,000 |
Greenwood is a different market. The Valley average is $394,019 against $592,675 in HRM, the Down Payment Assistance Program cap for the Valley is $375,000, and Berwick charges 1.25% deed transfer tax against 1.5% in Kentville and Kings County. The Valley in full →
How military income and allowances are read
Regular Force basic pay is clean salaried income: a pay statement and confirmation of service. Allowances are where lenders differ, and a lender that reads them correctly can approve a price another will not.
- A spouse’s income after the move. Income from a job that is ending does not count; a signed letter of employment at the new location usually does, often before the start date.
- Reserve Force income is assessed on two years of history. Documented Class B and Class C service reads much better than intermittent Class A.
Choose the term around the posting cycle, not the rate
If you expect to move again in two to four years, the rate on a five-year fixed matters less than what it costs to get out of it.
- Portability. A fully portable mortgage moves to the next property without penalty. Confirm the port window in writing; it varies from same-day to several months.
- The penalty. Breaking a fixed costs the greater of three months’ interest and the interest rate differential; a variable typically costs three months’ interest.
- Term length. A three-year term that expires near your expected posting date beats a five-year term broken mid-way.
- Blend and extend. If you port and need more, the increase is usually blended at current rates. Ask how the blend is calculated before you commit.
How it works
From first call to keys, in four steps
-
A 15-minute call
You say what you’re trying to do and roughly what you earn.
Riley tell you the price a lender will support, the cash you need to close, and what to fix first.
-
Documents and pre-approval
You send the short list through a secure upload link.
Riley package the file and come back with a pre-approval letter and a rate held 90 to 120 days.
-
Lenders, side by side
You read the comparison and pick.
Riley place one application with banks, credit unions and monolines, and show you every answer.
-
Approval, lawyer, keys
You sign with your own local lawyer.
Riley hold the lender, appraiser and lawyer to the closing date.
Why a broker
Licensed, independent, paid by the lender
- Licensed in Nova Scotia Associate broker 3001134, verifiable on the provincial register
- $0 broker fee On a standard residential mortgage the lender pays, not you
- Banks, credit unions, monolines One application, one credit check, placed with the lender that reads your file best
- Every part of the province Bedford office, remote process: Yarmouth to Sydney, the same four steps
Questions people ask
Do lenders count military allowances as income?
It varies by lender and by allowance. Regular Force basic pay is straightforward salaried income on a pay statement. Each allowance is assessed on whether it is permanent, taxable and continues at the new location.
Can I port my mortgage to my new posting?
Often, yes. Porting moves your rate and terms to the new property and avoids a prepayment penalty; most lenders allow a limited window between the sale closing and the purchase closing, with any increase blended at current rates. Arrange it before you sell, not after.
What happens if I am posted again in two years?
That question should shape the term, not the rate. A five-year fixed broken at year two carries an interest rate differential penalty that can be substantial. Price a shorter term, a fully portable mortgage or a variable rate against the posting cycle rather than the headline rate.
Do the Nova Scotia first-time buyer programs work for CAF members?
On the same terms as anyone else: residency in the province is not a condition, but the price caps are. Both cap at $570,000 in HRM and East Hants and $500,000 elsewhere, against a Halifax-Dartmouth average of $592,675 and an Annapolis Valley average of $394,019. They are far more usable around 14 Wing Greenwood than around CFB Halifax.

Still unsure? Ask me directly.
If your question isn't here, your situation is probably specific. Fifteen minutes on the phone beats reading another page, and nothing is pulled on your credit.
(902) 298-0218 · Monday to Friday, 8:00 am to 10:00 pm Atlantic
Send the posting message date and we will work backwards
You get a document list, a realistic pre-approval date, the cash-to-close figure for your posting and a term built around your next expected move.
(902) 298-0218 · Monday to Friday, 8:00 am to 10:00 pm Atlantic