Skip to content
Oickle Mortgages Powered by Indi, The Independent Mortgage Company Ltd.
The Halifax waterfront at first light, reflected in a calm harbour

A mortgage broker for all of Nova Scotia.

The lender that fits your file, not the branch you walked into.

Halifax Harbour

  • Licensed in Nova Scotia Associate broker 3001134, verifiable on the provincial register
  • $0 broker fee On a standard residential mortgage the lender pays, not you
  • Banks, credit unions, monolines One application, one credit check, placed with the lender that reads your file best
  • Every part of the province Bedford office, remote process: Yarmouth to Sydney, the same four steps

Truro property purchase example

Northern Nova Scotia average August 2026
Average home price
$332,251
Minimum down payment (5%)
$16,613
Deed transfer tax, Truro (1.5%)
$4,984
Other closing costs, est. 1% legal, appraisal, inspection
$3,323
Cash to buy
$24,919

Nova Scotia Association of REALTORS® publishes averages by region, not by town; Truro is in Northern Nova Scotia. Down payment at the insured minimum. Other closing costs are an estimate — no Nova Scotia source publishes legal, appraisal or inspection fees; your lawyer quotes them. Type your own price in the bar above.
Your broker

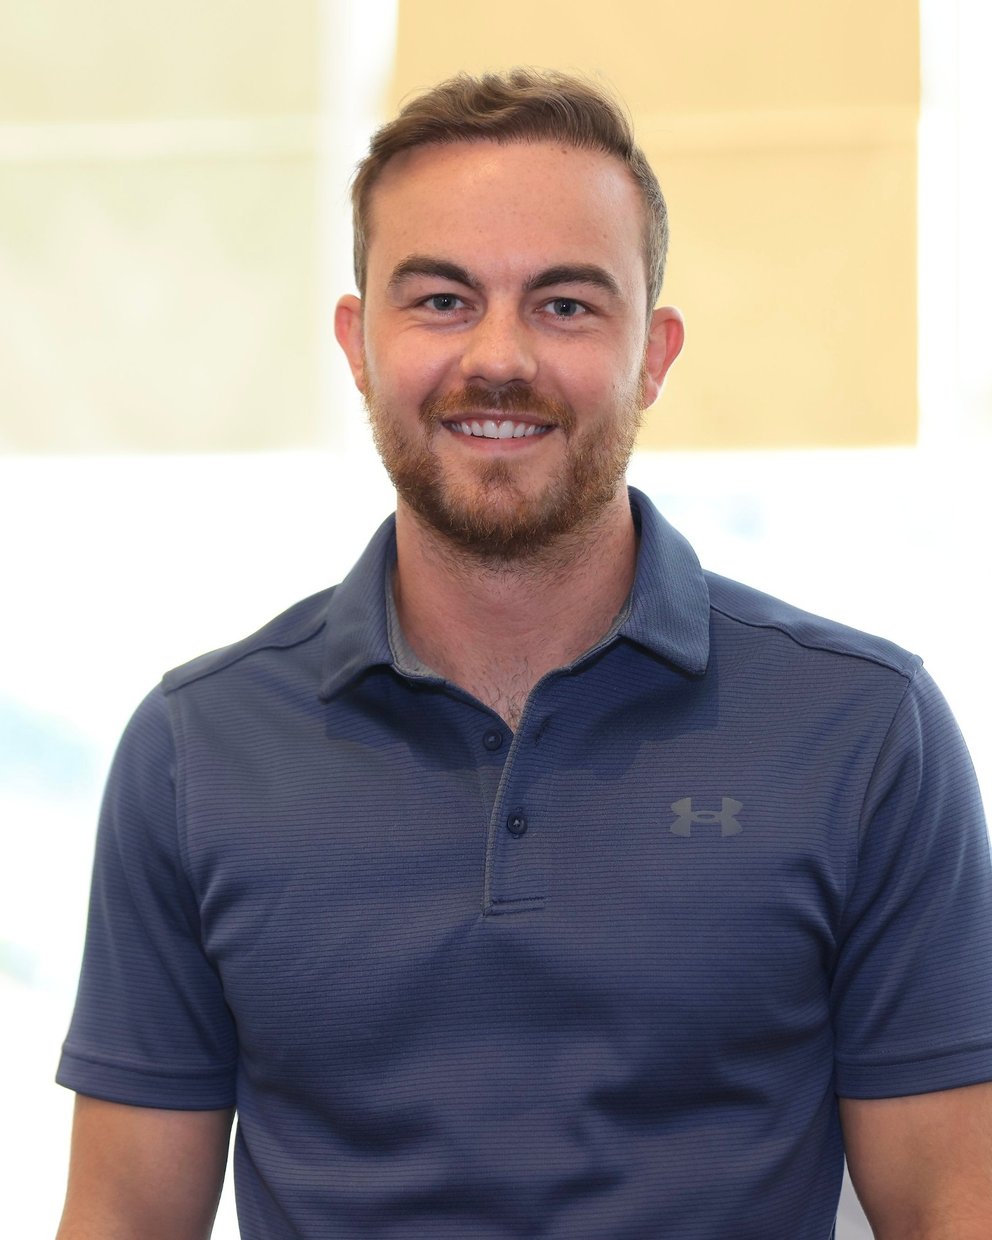
Riley Oickle, associate mortgage broker, Bedford, Nova Scotia

One broker, start to finish

I grew up in rural Nova Scotia, financed property across six Canadian markets and wrote a book on the arithmetic. You see every number before you sign anything. If your own bank is the better answer, I say so, and you pay nothing either way.

Riley Oickle · Associate Mortgage Broker, NS licence 3001134 · Bedford

Full profile and licence verification
Bank or broker

A bank sells its own mortgages. A broker shops 33 lenders.

Going to your bank
Your bank
Only that bank’s mortgages

1 lender · 1 rate sheet · 1 set of rules

Working with a mortgage broker
Mortgage broker

1 application
1 credit check

  • Banks 8

    • BMO
    • CIBC
    • Desjardins
    • National Bank
    • RBC Royal Bank
    • Scotiabank
    • TD
    • B2B Bank
  • Monoline lenders 10

    • CMLS Financial
    • First National Financial
    • MCAP
    • MERIX Financial
    • Radius Financial
    • RFA
    • RMG Mortgages
    • Strive Capital
    • Highclere Capital
    • Assumption Life
  • Alternative & B lenders 7

    • Equitable Bank
    • Home Trust
    • Haventree Bank
    • WealthONE Bank of Canada
    • Peoples Group
    • Community Trust
    • Indigo Blue
  • Private lenders 8

    • Firm Capital
    • MCAN Financial
    • Magenta Capital
    • Capital Direct
    • Alternative Financing Options
    • Atlantic Signature Mortgage & Loan
    • East Coast Private Lending
    • Graysbrook Capital

33 lenders and their products, from one conversation

Logos show lenders an application can be placed with through INDI THE INDEPENDENT MORTGAGE COMPANY LTD. They do not imply endorsement, and every approval is subject to that lender’s own criteria. See the full lender panel.

  • Lenders compared for you

    One application, one credit check, read against 33 lenders’ rules at once.
  • Rate and terms side by side

    Penalty, prepayment and portability compared, not just the headline rate.
  • Every kind of mortgage

    Purchase, renewal, refinance, self-employed, rental, and files a bank turned down.

  • Structured around you

    Term, amortization and product chosen for your income, plans and penalty risk.

  • Handled start to finish

    Documents, lender questions, appraisal and your lawyer — one person on it until you have keys.

  • $0 on a standard mortgage

    The lender pays the brokerage. Any fee on private lending is in writing before work starts.

How to choose a broker · What a broker costs · Mortgage broker in Halifax · A broker near you

Services we offer

First home

For you if you've never owned and want to know which of the two Nova Scotia programs you qualify for.

  • The two Nova Scotia programs: 2% down or a 5% interest-free loan
  • Insured mortgages from 5% down, and what the premium costs
  • FHSA, Home Buyers’ Plan and the first-time buyer tax credit
See how it works

Buying my next home

For you if you're moving and the sale and purchase have to line up.

  • Lining up the sale and the purchase, with a bridge loan when they don’t
  • Porting your rate and term, or breaking it, whichever costs less
  • Deed transfer tax, appraisal and lawyer, costed before you offer
See how it works

Renewing in the next 6 months

For you if your term ends soon and the bank has sent a renewal letter.

  • Whether the renewal letter is your lender’s best offer
  • Switching lenders, often at no cost, without a new stress test
  • Payout penalties and blended rates if you move before the term ends
See how it works

Refinance, HELOC or debt consolidation

For you if you have equity and a reason to use it — higher-rate debt, a renovation, a second property.

  • Borrowing to 80% of the appraised value, less the current balance
  • One payment in place of several higher-rate debts
  • A HELOC, priced off prime, when you want the room but not the debt
See how it works

Self-employed

For you if your income is real but your tax return understates it.

  • Two years of Notices of Assessment, and what lenders add back
  • Stated-income and B-lender routes when taxable income is low
  • Incorporated, sole proprietor, fishery and seasonal income
See how it works

Investment property (1–4 units)

For you if you're buying to rent, where the down payment and rental-income rules differ.

  • 20% down when you won’t live in it; less when you live in one unit
  • How much of the rent counts toward qualifying
  • Appraisal, leases and the down-payment source, checked before you offer
See how it works

Here’s what the process looks like

  • Your rate is held while you shop and close (steps 3–5)
  1. A first call 15 minutes No credit pulled, nothing to sign
  2. Documents in Income, credit, down payment, by secure upload
  3. Pre-approval 1–3 business days A maximum price and a letter behind your offer
  4. Full approval 5–10 business days On the specific house, from accepted offer to firm commitment
  5. Rate hold protects you 90–120 days Rates rise, you keep the hold; rates fall, you get the lower one

Typical Nova Scotia timings in our experience; the rate-hold length depends on the lender. The appraisal is the slowest step, longer on rural well-and-septic properties. Last verified September 20, 2026.

Questions people ask before they call

What does a mortgage broker cost in Nova Scotia?

Nothing, usually. On a standard residential mortgage the lender pays the brokerage when it funds, so you pay $0. A fee applies only on some private and alternative-lender mortgages; Nova Scotia regulation requires it in writing before you sign and bars collecting it until the lender confirms funding in writing. How brokers are paid, and when a fee can apply →

Can you help if my bank said no?

Often. One branch’s decline is that lender’s policy, not a verdict; the same application can go to credit unions, monolines and, where it fits, alternative or private lenders, each reading income and credit differently. Bring the reason for the no.

Does the stress test apply at renewal?

Only if you change the mortgage. Renewing with your current lender, you are not re-tested; since November 21, 2024 OSFI also exempts a straight switch to a new lender (same balance, same amortization) from the greater of the contract rate plus 2% and 5.25%. Taking equity out or extending the amortization is a tested refinance.

How long does the whole process take?

One to three business days once your documents are in, in our experience, holding a rate for typically 90 to 120 days. A full purchase approval usually runs five to ten business days from accepted offer to firm commitment; the appraisal is the slowest step, longer on rural well-and-septic properties.

Do I have to commit to anything to find out what I qualify for?

No. The first call costs nothing and pulls no credit. A credit check happens only after you sign a written consent, once, and the lender pays the brokerage only if a mortgage funds. If your own bank is the better answer, you are told so and the conversation ends there.

What is the difference between a mortgage loan broker and a bank?

A bank lends its own money against its own guidelines, so a no there is the end of it. A mortgage loan broker sends one application, on one credit inquiry, to the banks, credit unions and monoline lenders on a panel, and places it where it fits. Searches for mortgage brokers NS and mortgage broker Nova Scotia return the same licensed people; the province licenses mortgage brokers and associate mortgage brokers.

Do you work outside HRM?

Yes, all of Nova Scotia. Application, documents and signing are remote, so 64 towns and 7 regions are served the same way, each with its own page. Your appraiser and lawyer are local to the property.

Where do the figures on this page come from?

Each figure’s publisher: the Province of Nova Scotia (deed transfer tax, buyer programs), CMHC (premiums), OSFI (stress test), the Bank of Canada (policy rate), Nova Scotia Association of REALTORS® / CREA monthly statistics (prices) — checked by hand, last 2026-09-20. Every source, on one page →

Riley Oickle, associate mortgage broker

Still unsure? Ask me directly.

If your question isn't here, your situation is probably specific. Fifteen minutes on the phone beats reading another page, and nothing is pulled on your credit.

Book a 15-minute call

(902) 298-0218 · Monday to Friday, 8:00 am to 10:00 pm Atlantic

Ready when you are.

Fifteen minutes on the phone tells you what you qualify for, what closing will cost in your municipality, and whether a broker or your own bank is the better route. No fee, no credit check, no obligation.

Book a 15-minute call See what I qualify for

(902) 298-0218 · Monday to Friday, 8:00 am to 10:00 pm Atlantic