

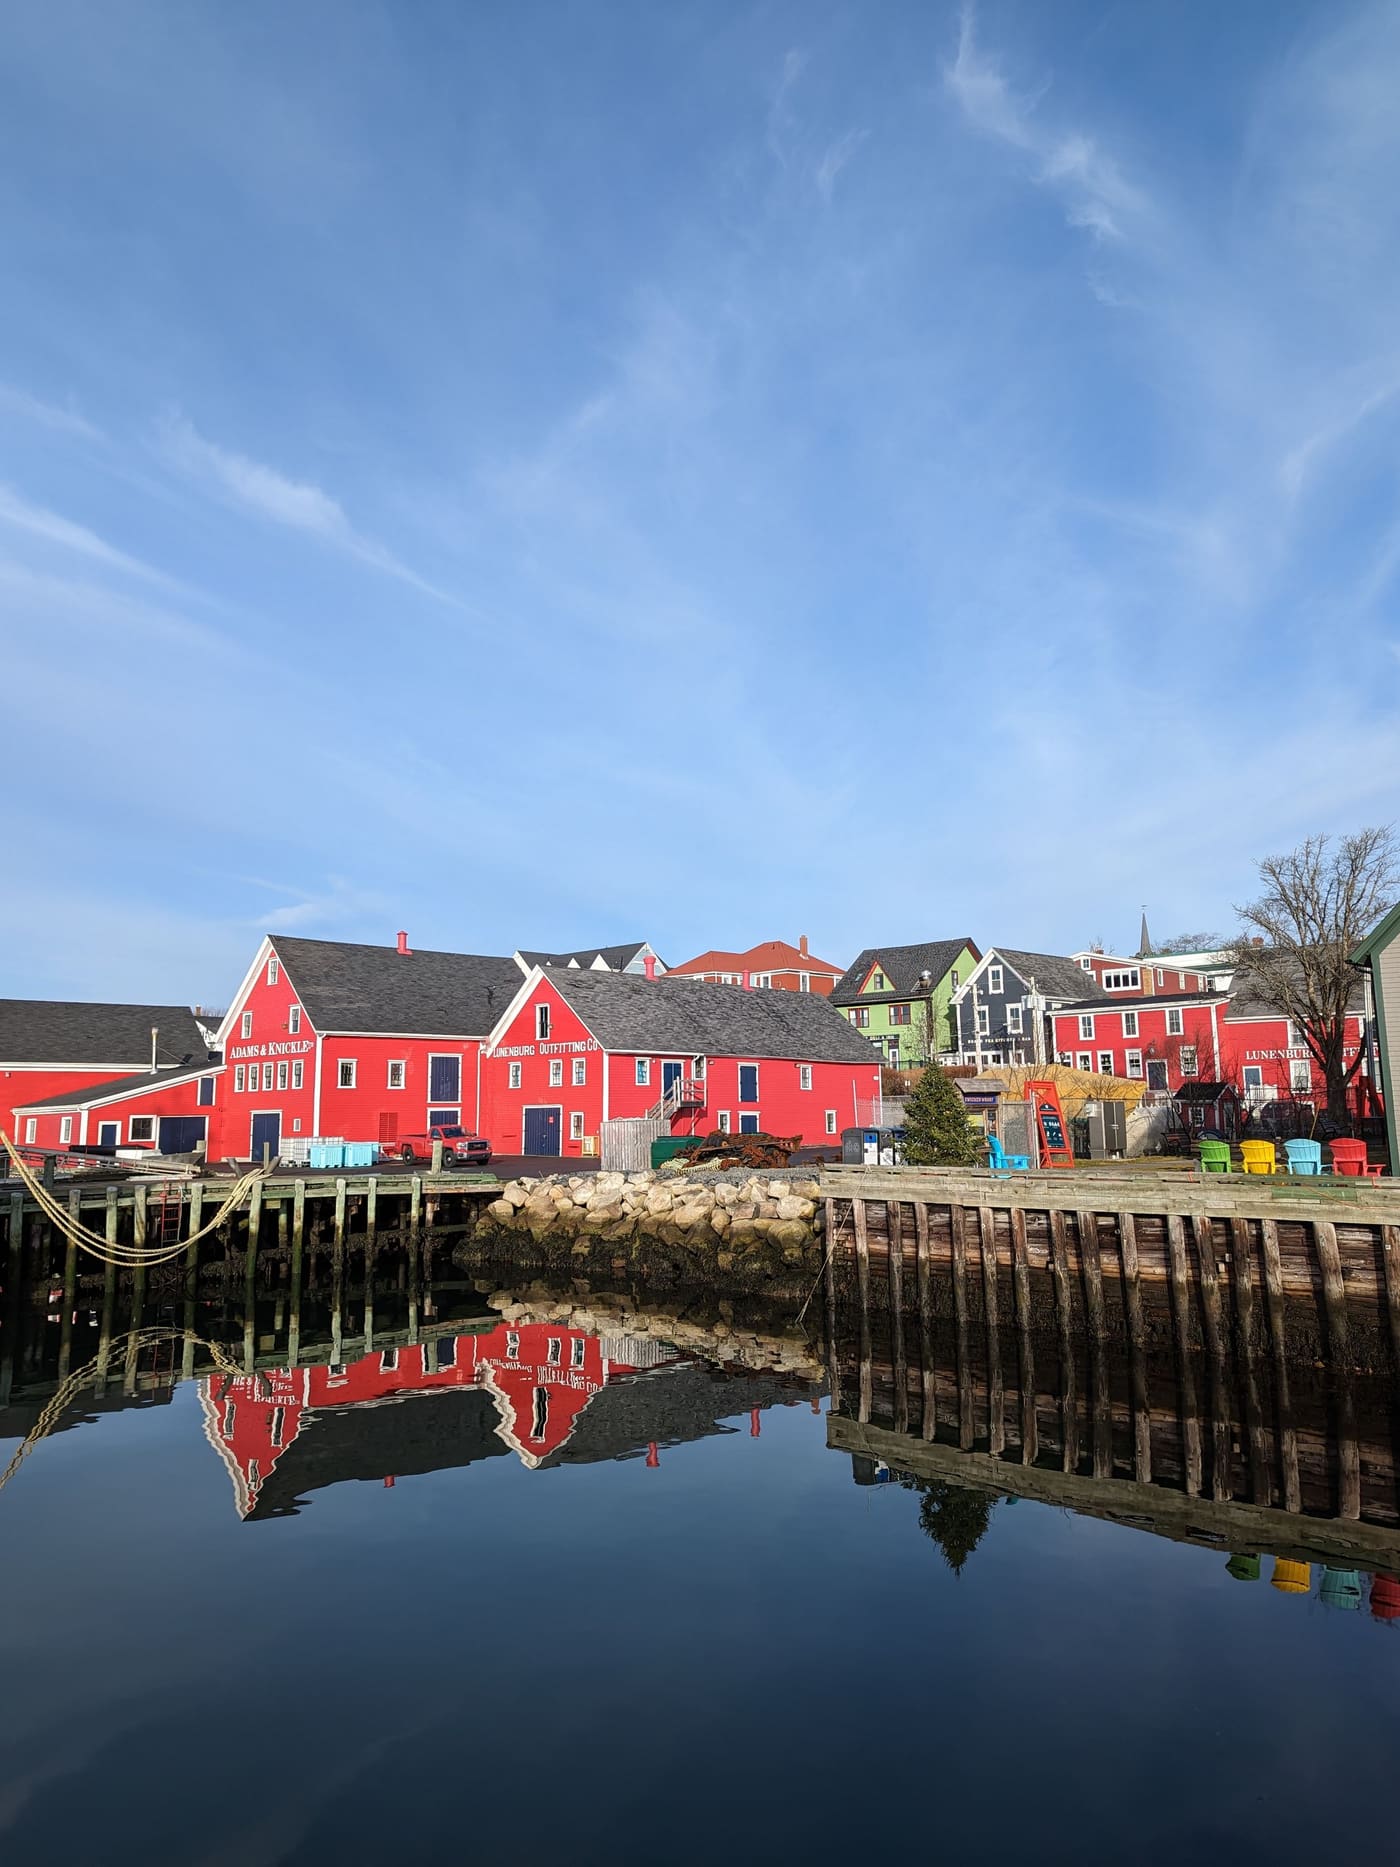
Lunenburg County · South Shore
Mortgage broker serving Lunenburg, Nova Scotia
Lunenburg is a UNESCO World Heritage town with housing stock to match, which makes it the Nova Scotia market where insurability decides the most purchases. It is also one of the few places where crossing a municipal line changes the tax: the town charges 1.5%, the District of Lunenburg around it charges 1.25% — one of only three municipalities in the province at that rate.
Lunenburg, South Shore
What does it cost to buy a home in Lunenburg?
Lunenburg is in Lunenburg County, in the South Shore housing region. On the August 2026 South Shore average of $455,127: minimum down payment $22,756, Town of Lunenburg deed transfer tax $6,827 at 1.5%, and roughly $31,083 cash to close with legal costs. The $449,665 mortgage, premium included, needs household income near $98,736 at the stress-test floor.
Looking for a mortgage broker, mortgage agent or mortgage advisor in Lunenburg? In Nova Scotia that is one licensed role, and the licence covers the whole province.
The tax in Lunenburg
Town of Lunenburg charges 1.5% deed transfer tax, paid at closing. It follows the property: Municipality of the District of Lunenburg 1.25%, Town of Mahone Bay 1.5%, Municipality of the District of Chester 1.5%, Town of Bridgewater 1.5%. Every municipality’s rate →
- Minimum down payment $22,756
- Town of Lunenburg deed transfer tax $6,827
- Legal, recording and title $1,500
Assumptions: 5%/10% minimum down payment, CMHC premium financed into the mortgage, 25-year amortization, qualifying at the 5.25% stress-test floor (or the contract rate plus 2% if higher), property tax about 1% of price, heat $150/month, GDS 39%. Legal $1,000, recording $200 and title insurance $300 are typical Nova Scotia figures, not quotes.
Which program fits here
The First-time Homebuyers Program (2–4% down, credit unions only) caps at $500,000 here; the Down Payment Assistance Program at $375,000. The $455,127 average sits above the DPAP cap, so most Lunenburg buyers fit only the first. Above $200,000 income or below 630 credit, neither fits; a standard insured mortgage with 5% down does. Check which programs you fit →
Refinancing or renewing a mortgage in Lunenburg
Already own in Lunenburg? Mortgage refinancing can go to 80% of the home’s appraised value: $364,102 on the South Shore average of $455,127. No deed transfer tax applies when the owner stays the same. At renewal, send the lender’s offer before you sign it and I will check it against other lenders.
Credit unions with a branch in Lunenburg
No credit union has a branch in Lunenburg; the nearest participating branch is East Coast Credit Union in Bridgewater. The banks and monoline lenders I place files with have no branch requirement. The province’s list of participating credit unions →
How I work with Lunenburg buyers
Lunenburg is about one hour and fifteen minutes from the office in Bedford. Lunenburg files run remotely with a South Shore appraiser and your own lawyer. How pre-approval works →
Go deeper
The detail, if you want it
The arithmetic on the South Shore average
| Purchase price | $455,127 |
| Minimum down payment | $22,756 |
| CMHC premium (4%, financed) | $17,295 |
| Mortgage amount | $449,665 |
| Town of Lunenburg deed transfer tax (1.5%) | $6,827 |
| Legal, recording and title (typical) | $1,500 |
| Cash to close | $31,083 |
| Monthly payment at 4.45% (chartered-bank prime rate, Bank of Canada, 2026-09-30), 25 years | $2,476 |
| Each quarter-point of rate on this mortgage | $63 a month |
| Monthly payment at the 5.25% qualifying rate (what you must qualify at, not what you pay) | $2,680 |
| Income needed to qualify | $98,736 |
Run it on a specific price → · Payment at your own rate → · Work backwards from your income →
What lenders ask about Lunenburg homes
- Much of the old town is eighteenth and nineteenth-century wood-frame, and insurers ask the hard questions before lenders do: knob-and-tube or aluminium wiring, sixty-amp service, oil tanks and wood stoves. A heritage house that cannot be insured cannot be mortgaged, whatever the appraisal says.
- Heritage designation and conservation-district rules can constrain what may be changed, which matters for a purchase-plus-improvements mortgage — the lender funds the work against an as-improved value, and the work has to be permitted before it can be valued.
- Outside the town, through the District of Lunenburg and toward New Germany and Petite Riviere, most properties are on well and septic, and some are seasonal. A cottage without year-round access or a permanent heat source is the harder file.
Income and closing in Lunenburg
- Tourism and hospitality income here is seasonal, and lenders average it over two years rather than annualising a strong summer. Two years of Notices of Assessment carry more weight than recent pay stubs.
- The fishery, boatbuilding and the marine trades supply skilled employment that is frequently self-employed or contract. Where taxable income is written down against real cash flow, an alternative lender reading bank statements is the usual route.
- A significant retired and second-home population buys here. Pension and investment income qualifies on pension statements and Notices of Assessment, and a property bought as a second home rather than a principal residence needs a larger down payment.
- No office visit required — application, uploads and signing are remote, and you use your own Lunenburg or Bridgewater lawyer.
- Deed transfer tax is 1.5% in the Town of Lunenburg and 1.25% in the Municipality of the District of Lunenburg immediately around it. On a $450,000 purchase that is a $1,125 difference for the same house a few minutes away.
- Get the insurance quote before the home inspection, not after. On heritage stock the insurer is the binding constraint, and finding out in the last week of a financing condition is how these deals fall apart.
Comparing mortgage brokers in Lunenburg
Nova Scotia licenses brokers for the whole province and ranks none of them, so check the licence, the number of lenders and any fee in writing. The four checks → · Broker, agent, advisor or specialist? →
Why a broker
Licensed, independent, paid by the lender
- Licensed in Nova Scotia Associate broker 3001134, verifiable on the provincial register
- $0 broker fee On a standard residential mortgage the lender pays, not you
- Banks, credit unions, monolines One application, one credit check, placed with the lender that reads your file best
- Every part of the province Bedford office, remote process: Yarmouth to Sydney, the same four steps
Questions people ask
How much is deed transfer tax in Lunenburg?
The Town of Lunenburg charges 1.5% of the purchase price, paid in cash on closing. The Municipality of the District of Lunenburg, which surrounds the town, charges 1.25% — one of only three municipalities in Nova Scotia at that rate, alongside Berwick and the District of St. Mary’s. The rate follows the property, not the buyer.
Can I get a mortgage on a heritage house in Lunenburg?
Yes, but the insurance comes first. Lenders require a binder naming them as mortgagee before they advance, so an older house that an insurer will not cover cannot close. Wiring, oil tanks and wood stoves are the usual sticking points. Get a quote on the specific property early in the financing condition.
Does the Down Payment Assistance Program work in Lunenburg?
Only below its cap. The South Shore band is $375,000, and the South Shore regional average sits above that. Many buyers here fit the First-time Homebuyers Program, whose cap outside Halifax is $500,000, and not the Down Payment Assistance Program.
Do I need to come to Bedford to get a mortgage in Lunenburg?
No. Lunenburg is about one hour and fifteen minutes from the office, and nothing in the file needs you there: application, uploads and signing are remote, an appraiser covering Lunenburg County does the appraisal, and you choose your own Lunenburg lawyer.

Still unsure? Ask me directly.
If your question isn't here, your situation is probably specific. Fifteen minutes on the phone beats reading another page, and nothing is pulled on your credit.
(902) 298-0218 · Monday to Friday, 8:00 am to 10:00 pm Atlantic
Buying, building or renewing in Lunenburg?
Send the listing or your renewal statement. You get back the Lunenburg tax, the cash to close, which program you fit and what the file needs — within a business day, at no fee.
(902) 298-0218 · Monday to Friday, 8:00 am to 10:00 pm Atlantic