
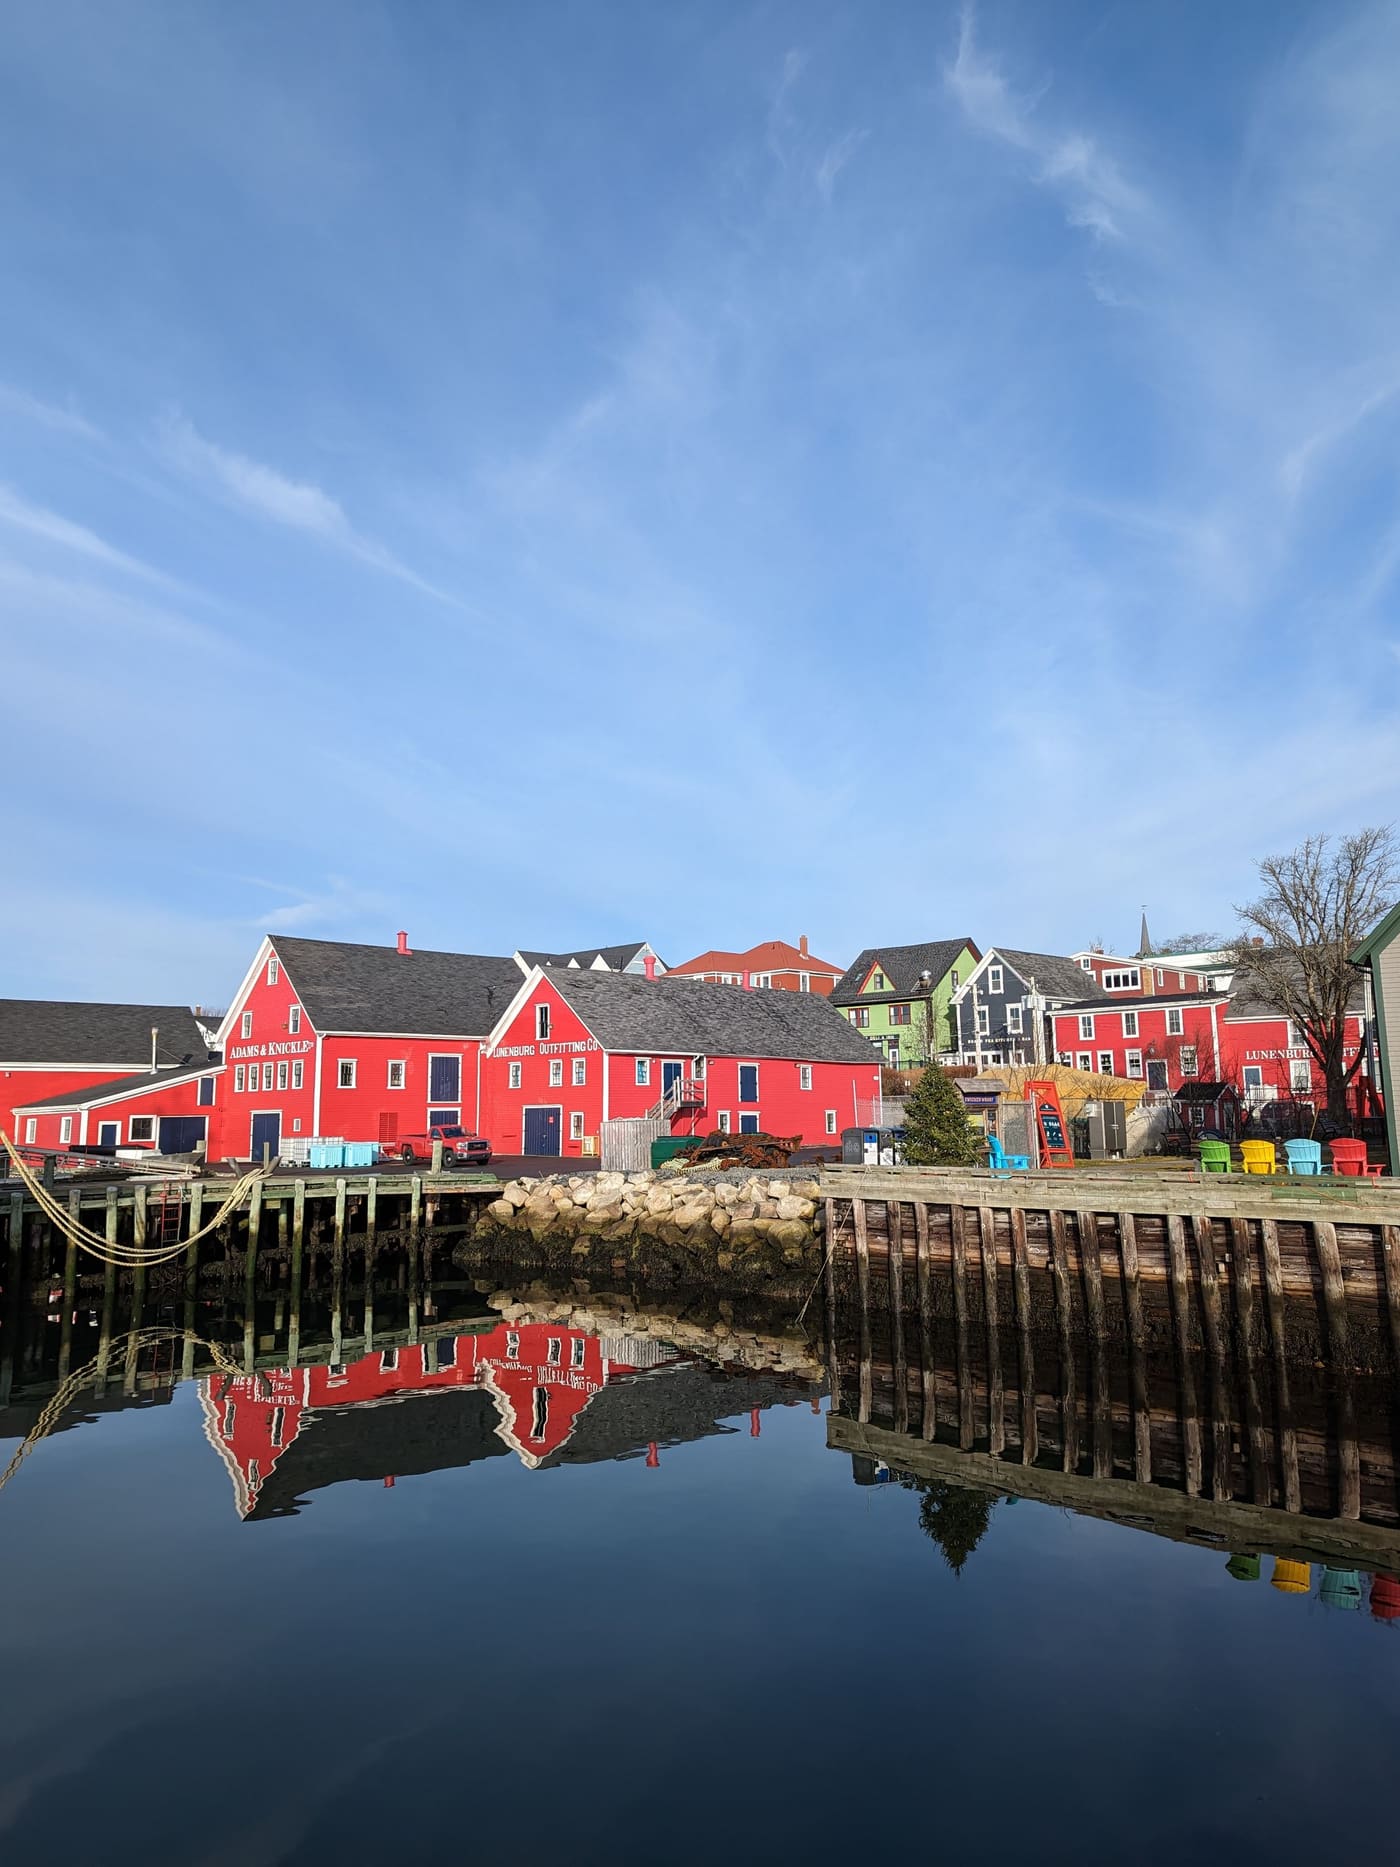
Lunenburg, South Shore
How to find a mortgage broker in Nova Scotia, and how to tell a good one
Search results rank pages, not brokers. Here is what is actually checkable about a Nova Scotia broker before you hand over your income documents, and the questions that separate a good one from a friendly one.
How do I choose a mortgage broker in Nova Scotia?
There is no official ranking. Nova Scotia licenses brokers; it does not rate them, and the "best broker" lists are directories and paid placements. Judge on four things you can verify: a current licence on the provincial public register, how many lenders the brokerage can place your file with, whether you get the rate and the penalty type in writing, and whether the fee disclosure arrives before any work starts.
The four checks, and where to make them
Each of these takes a minute and none of them depends on anyone's opinion.
- The licence. Search the register of licensed brokers and associate mortgage brokers for the person by name, and the brokerage register for the company. You want the licensed name, a licence number, an active status and the current year. A broker who cannot tell you their number without looking it up is a bad sign.
- The lender panel. Ask how many lenders the brokerage is signed with and which three they expect to use for your file. A bank employee has one. A broker who names one lender for every file is functioning as one.
- The written quote. Ask for the rate, term, amortization, payment, rate-hold expiry, penalty type and prepayment privileges in writing. Two mortgages at the same rate are not the same mortgage.
- How they are paid. On a standard residential mortgage the lender pays the brokerage and you pay nothing. If a fee to you is coming, it must be disclosed in writing first, and under the Standards of Conduct regulations it cannot be collected until the lender has confirmed funding in writing.
Why the "best broker" lists are not a shortlist
Search "best mortgage broker" in any Nova Scotia town and you get three kinds of result: directories that list whoever pays or claims a profile, review aggregators where a handful of reviews decides the order, and brokers' own pages calling themselves the best. None of them is an assessment. The provincial regulator publishes a register, not a league table.
This page is written by a broker, so treat its opinion the same way. What it can give you that a list cannot is the four checks above — run them on Riley too.
A rate is not a quote
| Comparison | What you are usually shown | What you should ask for |
|---|---|---|
| Rate | A number, sometimes without the term | Rate, fixed or variable, term, and the rate-hold expiry date |
| Payment | The monthly payment | The payment, the amortization behind it, and the qualifying payment |
| Penalty | Not mentioned | IRD or three months interest, and which posted rate the IRD is calculated against |
| Prepayment | Not mentioned | The lump-sum and payment-increase privileges, as percentages |
| Cost to you | "No fee" | The fee in writing if there is one, with the disclosure attached |
Go deeper
The detail, if you want it
The five questions to ask on the first call
- How many lenders can you place this file with, and which one do you expect to use? You want a number and a name, with a reason attached to the file rather than to the lender.
- How are you paid on this one, and will I pay anything? Lender-paid on a standard residential mortgage. Any borrower fee should arrive in writing before anything else happens.
- What is the penalty type on the mortgage you are recommending? Interest rate differential or three months interest, and against which rate. This is the question most people learn to ask too late.
- What are the prepayment privileges? The annual lump sum and payment increase you are allowed, as percentages.
- What could make this fall apart before closing? A good answer is specific to your file — probation, a car loan, a rural water test, an appraisal gap — not "nothing, you're approved".
Broker, agent, advisor or bank specialist?
In Nova Scotia the regulated titles are mortgage brokerage, mortgage broker and associate mortgage broker. "Mortgage agent", "mortgage advisor" and "mortgage consultant" are informal labels people use for the same regulated role, and provinces differ: Ontario uses agent and broker as two licence levels, Nova Scotia does not. A bank's "mortgage specialist" is an employee of one lender.
Should you talk to more than one?
Talk to as many as you like. Apply with one. Each application can mean a credit inquiry, and two brokers usually approach the same short list of lenders, which can get a file flagged as shopped and occasionally declined for it. The point of a broker is that one application and one inquiry reach many lenders; running two brokers in parallel gives that up.
If you want a second opinion on an offer you already have, ask for it as a second opinion. Send the commitment and ask what is wrong with it.
Running the checks on Riley
- Licence. Riley Oickle, associate mortgage broker, licence 3001134, with INDI THE INDEPENDENT MORTGAGE COMPANY LTD., brokerage licence 3000688. Both are on the provincial registers, linked from the licensing page.
- Lender panel. Banks, Atlantic credit unions and monoline lenders through the brokerage — the panel, and how one gets chosen.
- Written quote. Rate, term, penalty type and privileges in writing before you commit, and the Form 1 disclosure before any services.
- Cost. $0 on a standard residential mortgage — how that works, and the two cases where it does not.
- Where. All of Nova Scotia, from 30 Damascus Rd, Suite 212, Bedford. Your town, and what is specific to it.
Written by Riley Oickle
Associate Mortgage Broker, Nova Scotia licence 2025-3001134, with Indi, The Independent Mortgage Company Ltd. Every figure on this page links to the government or regulator page it came from.
Why a broker
Licensed, independent, paid by the lender
- Licensed in Nova Scotia Associate broker 3001134, verifiable on the provincial register
- $0 broker fee On a standard residential mortgage the lender pays, not you
- Banks, credit unions, monolines One application, one credit check, placed with the lender that reads your file best
- Every part of the province Bedford office, remote process: Yarmouth to Sydney, the same four steps
Questions people ask
Who is the best mortgage broker in Nova Scotia?
Nobody can answer that honestly, because there is no official ranking: the province licenses brokers, it does not rate them, and the "best broker" lists you find are directories and paid placements. What you can check is objective — a current licence on the provincial public register, how many lenders the brokerage can actually place a file with, whether you get the rate and the penalty type in writing, and whether the fee disclosure comes before any work.
How do I check that a mortgage broker is licensed in Nova Scotia?
Search the provincial public register of licensed mortgage brokers and associate mortgage brokers by name. You should find the person under their licensed name, with a licence number, a brokerage and an active status. Brokerages are on a separate register. Every Nova Scotia mortgage licence expires 31 October and is renewed for the following year, so check the year on the record as well as the name.
What questions should I ask a mortgage broker?
Five that matter: how many lenders can you place this file with, and which one do you expect to use; how are you paid on it, and will I pay anything; what is the penalty type on the mortgage you are recommending, IRD or three months interest; what are the prepayment privileges; and what could make this fall apart before closing. A broker who answers all five in writing is doing the job.
What should a mortgage broker quote include?
The lender, the rate and whether it is fixed or variable, the term, the amortization, the payment, the rate-hold expiry, the penalty type, the prepayment privileges, and any fee to you with the disclosure attached. A rate on its own is not a quote: two mortgages at the same rate can differ by thousands of dollars in penalty if you need to leave early.
Is it worth talking to more than one broker?
Talking, yes. Applying with more than one at the same time, rarely: each application can mean a credit inquiry, and two brokers often approach the same lenders, which can get a file flagged as shopped. Interview as many as you like, then let one place the file with many lenders on one inquiry.
Does speaking to a mortgage broker cost anything or affect my credit?
No on both counts at the first conversation. A discussion, a rough affordability read and a look at your renewal letter involve no credit pull and no fee. Credit is only pulled with your written consent when you decide to apply, and on a standard residential mortgage the broker fee to you is $0 because the lender pays the brokerage at funding.
How quickly can I speak to a mortgage broker?
Riley replies to a form or a call within 1 business day, and the first call is about 15 minutes. If you already have a renewal letter or a listing, send it with the message and the first reply can contain real numbers rather than a scheduling request.
Still unsure? Ask me directly.
If your question isn't here, your situation is probably specific. Fifteen minutes on the phone beats reading another page, and nothing is pulled on your credit.
(902) 298-0218 · Monday to Friday, 9:00 am to 5:00 pm Atlantic
Sent. Thank you.
Your details went straight to Riley. He replies within one business day, usually sooner, by phone or email.
Need it faster? Call (902) 298-0218, Monday to Friday, 9:00 am to 5:00 pm Atlantic.
Ask the five questions
Send your situation in three fields. You get back which lenders fit the file, how the brokerage is paid on it, and what the penalty type would be — in writing, within 1 business day, before you commit to anything.
(902) 298-0218 · Monday to Friday, 9:00 am to 5:00 pm Atlantic