
Digby County · Yarmouth
Mortgage broker serving Digby, Nova Scotia
Digby is a ferry town and a fishery town, and the municipal line around it carries the largest proportional tax difference in this part of the province: the town charges 1.5%, the District of Digby and Clare next door charge 1.0%. On the lowest regional prices in Nova Scotia, that is the difference between fitting a programme cap and missing it.
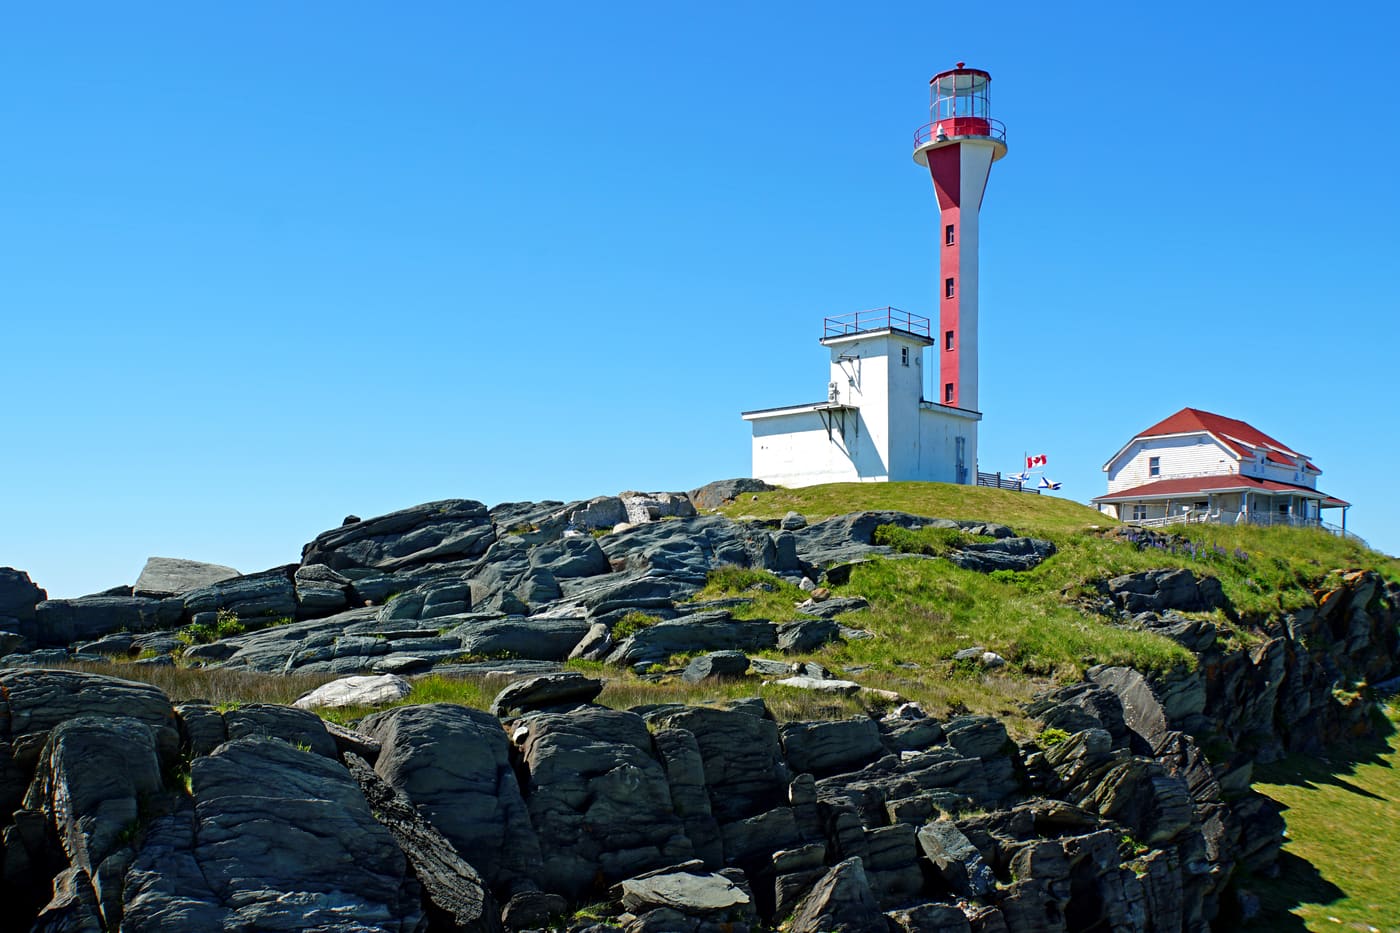
Cape Forchu, Yarmouth
What does it cost to buy a home in Digby?
Digby is in Digby County, in the Yarmouth housing region. On the August 2026 Yarmouth average of $313,944: minimum down payment $15,697, Town of Digby deed transfer tax $4,709 at 1.5%, and roughly $21,906 cash to close with legal costs. The $310,177 mortgage, premium included, needs household income near $69,539 at the stress-test floor.
The tax in Digby
Town of Digby charges 1.5% deed transfer tax, paid at closing. It follows the property: Municipality of the District of Digby 1%, Municipality of the District of Clare 1%. Every municipality’s rate →
- Minimum down payment $15,697
- Town of Digby deed transfer tax $4,709
- Legal, recording and title $1,500
Assumptions: 5%/10% minimum down payment, CMHC premium financed into the mortgage, 25-year amortization, qualifying at the 5.25% stress-test floor (or the contract rate plus 2% if higher), property tax about 1% of price, heat $150/month, GDS 39%. Legal $1,000, recording $200 and title insurance $300 are typical Nova Scotia figures, not quotes.
Which program fits here
The First-time Homebuyers Program (2–4% down, credit unions only) caps at $500,000 here; the Down Payment Assistance Program at $300,000. The $313,944 average sits above the DPAP cap, so most Digby buyers fit only the first. Above $200,000 income or below 630 credit, neither fits; a standard insured mortgage with 5% down does.
Go deeper
The detail, if you want it
The arithmetic on the Yarmouth average
| Purchase price | $313,944 |
| Minimum down payment | $15,697 |
| CMHC premium (4%, financed) | $11,930 |
| Mortgage amount | $310,177 |
| Town of Digby deed transfer tax (1.5%) | $4,709 |
| Legal, recording and title (typical) | $1,500 |
| Cash to close | $21,906 |
| Monthly payment at 4.45% (chartered-bank prime rate, Bank of Canada, 2026-09-16), 25 years | $1,708 |
| Monthly payment at the 5.25% qualifying rate (what you must qualify at, not what you pay) | $1,848 |
| Income needed to qualify | $69,539 |
Run it on a specific price → · Payment at your own rate →
Worked start to finish: Yarmouth first-time buyer: 5% DPAP loan and 1% deed tax (illustrative examples on this region’s figures).
What lenders ask about Digby homes
- Most of the stock is older wood-frame, much of it oil-heated with wood as a second source. Nova Scotia sets no service-life limit on a domestic oil tank — insurers set their own and do not publish them — so the tag on the tank is what the insurance quote turns on.
- Outside the town, through the District of Digby and Clare, homes are almost all on well and septic. Lenders want a potability test and evidence the septic works, and the full chemistry panel is worth running because arsenic and uranium are prevalent in Nova Scotia groundwater.
- Waterfront and seasonal properties are common and are the harder files: a lender may reduce the loan-to-value on a property without year-round access or a permanent heat source, and some will not lend at all.
Income and closing in Digby
- The fishery drives the local economy, and fishing income is seasonal and frequently self-employed. Lenders average two years of returns; a strong single season does not qualify on its own.
- The ferry, the wharf and the processing plants supply hourly employment with heavy seasonal overtime, which is averaged rather than annualised. Two years of T4s is what the file needs.
- Clare is an Acadian francophone community with a long tradition of self-employment in the trades and the fishery. Where the taxable figure understates real cash flow, a bank-statement programme with an alternative lender is the route, at a cost.
- Everything is handled remotely — application, uploads and e-signing — and you use your own Digby lawyer.
- Deed transfer tax is 1.5% in the Town of Digby, and 1.0% in both the Municipality of the District of Digby and the Municipality of the District of Clare. On a $250,000 purchase that is $3,750 against $2,500 for crossing the town boundary.
- Appraisals take longer here than almost anywhere in the province because recent comparable sales are thin, particularly on waterfront. Build a longer financing condition into any offer in Digby County.
How it works
From first call to keys, in four steps
-
A 15-minute call
You say what you’re trying to do and roughly what you earn.
Riley tell you the price a lender will support, the cash you need to close, and what to fix first.
-
Documents and pre-approval
You send the short list through a secure upload link.
Riley package the file and come back with a pre-approval letter and a rate held 90 to 120 days.
-
Lenders, side by side
You read the comparison and pick.
Riley place one application with banks, credit unions and monolines, and show you every answer.
-
Approval, lawyer, keys
You sign with your own local lawyer.
Riley hold the lender, appraiser and lawyer to the closing date.
Why a broker
Licensed, independent, paid by the lender
- Licensed in Nova Scotia Associate broker 3001134, verifiable on the provincial register
- $0 broker fee On a standard residential mortgage the lender pays, not you
- Banks, credit unions, monolines One application, one credit check, placed with the lender that reads your file best
- Every part of the province Bedford office, remote process: Yarmouth to Sydney, the same four steps
Questions people ask
How much is deed transfer tax in Digby?
The Town of Digby charges 1.5% of the purchase price. The Municipality of the District of Digby and the Municipality of the District of Clare both charge 1.0% — two of only fifteen municipalities in Nova Scotia at that rate. The rate follows the property, so a house just outside the town line costs a third less in tax.
Does the Down Payment Assistance Program work in Digby?
Yes, and this is one of the markets where it fits. The cap for Yarmouth County and the Northern and Eastern regions is $300,000, and the Yarmouth regional average sits below it. The programme is a 5% interest-free loan repaid over ten years, for households under $145,000 with credit of 650 or better, and it needs an insured pre-approval first.
Can I get a mortgage on fishing income in Digby?
Yes. Lenders and insurers use a two-year average of declared income, so you need two years of Notices of Assessment and T1 Generals rather than a single strong season. If you write off most of your income, a bank-statement programme with an alternative lender is the other route — at a higher rate, and worth comparing properly.
Do I need to come to Bedford to get a mortgage in Digby?
No. Application, uploads and signing are remote, an appraiser covering Digby County does the appraisal, and you choose your own Digby lawyer. Riley works province-wide from Bedford.
What does a mortgage broker cost in Digby?
Nothing on a standard residential mortgage: the lender pays the brokerage when it funds. A fee can apply only on private or some alternative lending, and Nova Scotia regulation requires it in writing before any services are provided.
Still unsure? Ask me directly.
If your question isn't here, your situation is probably specific. Fifteen minutes on the phone beats reading another page, and nothing is pulled on your credit.
(902) 298-0218 · Monday to Friday, 9:00 am to 5:00 pm Atlantic
Sent. Thank you.
Your details went straight to Riley. He replies within one business day, usually sooner, by phone or email.
Need it faster? Call (902) 298-0218, Monday to Friday, 9:00 am to 5:00 pm Atlantic.
Buying, building or renewing in Digby?
Send the listing or your renewal statement. You get back the Digby tax, the cash to close, which program you fit and what the file needs — within a business day, at no fee.
(902) 298-0218 · Monday to Friday, 9:00 am to 5:00 pm Atlantic