Skip to content
Oickle Mortgages Powered by Indi, The Independent Mortgage Company Ltd.
Home › Mortgage glossary
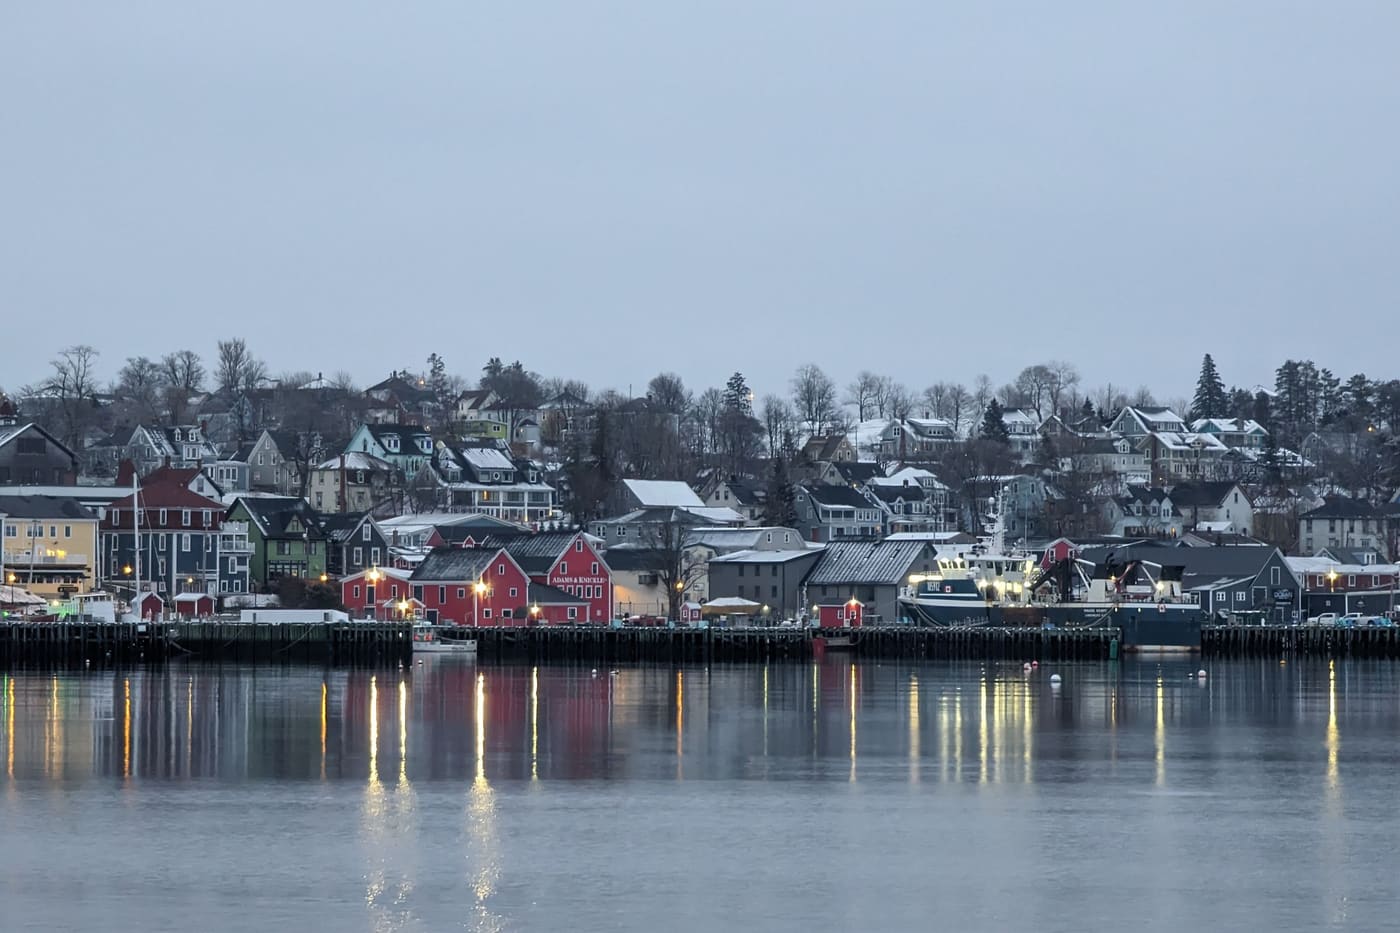
Houses climbing the hill above Lunenburg harbour on a winter evening

Lunenburg, South Shore

Mortgage glossary for Canada and Nova Scotia · 138 terms · updated October 3, 2026

Mortgage terms, in plain English

The words lenders, lawyers and brokers use, defined the way you would explain them at a kitchen table — with the Nova Scotia rules that change the answer.

What do the terms in my mortgage paperwork mean?

Most come down to five ideas: how much you borrow against the home’s value (loan-to-value), how long the contract and the payoff run (term and amortization), what you qualify for (the stress test and the 39% and 44% debt ratios), what it costs to leave early (the penalty), and what you pay on closing day. All are defined below.

138
Mortgage terms defined, A to Z
21
Specific to Nova Scotia, marked NS
82
Link to a full page on the topic
7
Topics to filter by

Mortgage terms in Canada, A to Z

Search, filter by topic, or jump to a letter. Every term has its own link: copy it from the term’s name to share it.

Mortgage terms starting with A

Lenders & brokers

A lender

Also called: Prime lender, A-lender

The mainstream end of the market: the big banks, most credit unions and the main monoline lenders, which mostly work through brokers. A lenders offer the lowest rates and follow the standard rulebook closely — the stress test, debt service ratios of 39% and 44% on insured files, verified income and solid credit.

If your file fits that rulebook, an A lender is almost always the cheapest place for it. If it does not, the next stop is a B lender, not a flat no.

Mortgage lenders in Nova Scotia

Related: B lender · Monoline lender · Credit union · Private mortgage

Rates, terms & payments

Accelerated bi-weekly payments

Also called: Accelerated weekly payments

Your monthly payment cut in half and paid every two weeks. A year has 26 two-week periods, so you make the equivalent of 13 monthly payments instead of 12, and the extra one goes entirely to principal. It shortens your amortization without changing the rate.

Plain bi-weekly is different: the monthly amount times 12, divided by 26. That only changes the timing of your payments, not how fast the balance falls.

Mortgage payment calculator

Related: Payment frequency · Amortization · Prepayment privileges · Principal

Buying a home

Agreement of purchase and sale

Also called: Purchase agreement, Offer to purchase

The signed contract between you and the seller: the price, the deposit, the closing date, what is included, and the conditions you can still walk away on. Your lender needs a full copy, including every amendment, before it will issue a firm approval.

In Nova Scotia most agreements use the standard REALTOR® form, with conditions such as financing, a home inspection and, on rural property, a well water test written in with their own deadlines.

Related: Financing condition · Going firm · Deposit · Closing date

Rates, terms & payments

Amortization

Also called: Amortization period

The total time it would take to pay your mortgage down to zero if nothing changed. It is not your term: the term is the length of the contract you sign now, the amortization is the whole road.

On an insured mortgage the maximum is 25 years, or 30 years for first-time buyers and buyers of a newly built home. A longer amortization lowers the payment and raises the total interest you pay; a shorter one does the opposite.

See how amortization changes your payment

Related: Mortgage term · Principal · Accelerated bi-weekly payments · Insured mortgage

Rates, terms & payments

Annual percentage rate (APR)

Also called: APR, Cost of borrowing

Your interest rate with the mandatory fees folded back in, expressed as a single yearly figure so two offers built differently can be compared. Lenders must show it in the cost-of-borrowing disclosure you receive before you sign.

On a standard bank or credit union mortgage with no fees, the APR sits on top of the rate. It matters most on private and some alternative mortgages, where a lender fee and a broker fee can turn a reasonable-looking rate into something much more expensive.

Related: Interest rate · Broker fee · Private mortgage · B lender

Closing & legal

Appraisal

Also called: Property appraisal, Valuation

An independent opinion of what the property is worth, ordered by the lender so it knows what it is lending against. It is not a home inspection and says nothing reliable about the roof or the furnace.

It usually takes 2–7 days, longer in rural Nova Scotia where comparable sales are thin. If it comes in below the price, the lender lends on the lower figure and the gap comes out of your pocket — which is why a low appraisal on a refinance or a private sale can reshape a whole file.

How long mortgage approval takes

Related: Home inspection · Loan-to-value (LTV) · Subject property · Conditional approval

Qualifying & credit

Arrears

Also called: Payment arrears, Tax arrears

Payments that are overdue: on the mortgage, on a loan, on property tax, or to the Canada Revenue Agency. Lenders look hard at property tax and CRA arrears in particular, because both can take priority over a mortgage on title.

Arrears do not end a file on their own. Most often they are paid out of a refinance at closing, or paid down first so the lender can see they are current.

Mortgages when the bank says no

Related: Default · Refinance · Lien · B lender

Closing & legal NS

Assessed value

Also called: Property assessment, PVSC assessment

The value Property Valuation Services Corporation puts on every Nova Scotia property each year, used to calculate property tax. It is neither the market price nor the appraisal, and it can sit well below either.

It matters in two places a buyer meets it: the capped assessment comes off after most sales, so the tax bill can jump; and the non-resident deed transfer tax is charged on the higher of the purchase price and the assessed value.

Capped assessment: the tax shock after you buy

Related: Capped Assessment Program (CAP) · Property tax · Non-resident deed transfer tax · Appraisal

Lenders & brokers NS

Associate mortgage broker

A Nova Scotia licence class for an individual who arranges mortgages through a licensed mortgage brokerage, under its supervision. Every licence in the province expires on 31 October and must be renewed each year, and each one can be checked on the provincial public register.

Riley Oickle is an associate mortgage broker, licence 3001134, with Indi, The Independent Mortgage Company Ltd., brokerage licence 3000688.

Licensing and how to check it

Related: Mortgage broker · Mortgage brokerage · Broker fee

Buying a home

Assumable mortgage

A mortgage the buyer takes over from the seller, keeping its rate, balance and remaining term instead of arranging a new one. It can look like a bargain when the seller locked in low.

Two things usually stop it. The lender still has to approve you as if you were applying fresh, and you have to fund the whole difference between the assumed balance and the price yourself — down payment and equity together, in cash.

Related: Porting · Mortgage term · Down payment

Alternative lender see B lender

Mortgage terms starting with B

Lenders & brokers

B lender

Also called: Alternative lender, B-lender, Subprime lender

A lender that approves files the banks will not: income that is real but hard to document, a recent consumer proposal, bruised credit, debt ratios over the standard limits, or an unusual property. Most are trust companies and some credit unions, and most of them deal only through brokers.

The price is a higher rate than an A lender and usually a lender fee. A B lender is best used as a bridge: a term or two to fix whatever kept you out of the A market, then a move back at renewal.

B-lenders and alternative lending, explained

Related: A lender · Private mortgage · Stated income · Consumer proposal

Rates, terms & payments

Bank of Canada policy rate

Also called: Overnight rate, Key interest rate, Target for the overnight rate

The interest rate the Bank of Canada sets to steer the economy. It was 2.25% after the September 2, 2026 decision; the next scheduled announcement is October 28, 2026.

The banks' prime rate moves with it, usually the same day or the next, so variable-rate mortgages and HELOCs follow it directly. Fixed rates do not: they track Government of Canada bond yields, which can move before or against the Bank.

Nova Scotia mortgage rates today

Related: Prime rate · Variable rate · Fixed rate · HELOC (home equity line of credit)

Qualifying & credit

Bankruptcy

A legal process, run through a Licensed Insolvency Trustee, that releases you from most unsecured debts in exchange for giving up certain assets and income for a period. It stays on your credit report for years after discharge.

It does not rule out a mortgage for good. Most lenders want the bankruptcy discharged and new credit opened and paid perfectly since; some alternative lenders will act sooner at a higher rate. The rebuilding starts the month after discharge, not the month before you apply.

Mortgages after a proposal or bankruptcy

Related: Consumer proposal · Credit score · B lender · Private mortgage

Equity, refinancing & renewal

Blend and extend

Also called: Blended rate

Instead of breaking your mortgage and paying a penalty, your lender mixes your current rate with today's rate and starts a new term at the weighted result. It is one way to borrow more, or lock in longer, mid-term.

The penalty does not disappear; it is folded into the blended rate. Ask the lender for the arithmetic in writing and compare it with breaking the mortgage outright or adding a second mortgage before you agree.

Breaking your mortgage, and when leaving pays

Related: Prepayment penalty · Refinance · Second mortgage · Porting

Rates, terms & payments

Blended payment

The standard Canadian mortgage payment: one fixed amount that covers both interest and principal. Early in the amortization most of each payment is interest; the share going to principal grows with every payment.

That is why a prepayment made early does more work than the same amount made late. It removes principal that would otherwise have been charged interest for decades.

Related: Principal · Interest rate · Amortization · Prepayment privileges

Buying a home

Bridge financing

Also called: Bridge loan

Short-term money for when your purchase closes before your sale does. It is a short-term loan secured against the home you are selling, advanced on your purchase closing day and repaid out of the sale proceeds when the sale closes.

It needs a firm, unconditional sale on the home you are selling — an accepted offer with conditions still on it is not enough for most lenders. Often the cheaper fix is moving one of the two closing dates. Canadian Armed Forces members relocating under the CAF Relocation Directive can have the interest reimbursed.

Bridge financing in Nova Scotia

Related: Closing date · Porting · Going firm · Down payment

Lenders & brokers NS

Broker fee

Also called: Brokerage fee, Lender fee

On a standard residential mortgage there is no broker fee: the lender pays the brokerage when the mortgage funds. A fee to the borrower applies only on some private and alternative files.

Nova Scotia regulates it closely. Under Section 22 of the Standards of Conduct for Mortgage Brokerages Regulations, a fee must be disclosed in writing, and cannot be charged or collected until the lender has confirmed funding in writing and you have accepted the commitment.

What a mortgage broker costs in Nova Scotia

Related: Mortgage broker · Annual percentage rate (APR) · Private mortgage · B lender

Builder’s lien see Lien

Mortgage terms starting with C

Closing & legal NS

Capped Assessment Program (CAP)

Also called: CAP, Capped assessment

A Nova Scotia rule that limits how fast a long-time owner's residential assessment can rise — 2.6% for 2026. The catch for buyers: the cap is removed in the year after a sale to anyone other than a family member, so the assessment resets toward market value and the tax bill can jump the year after you buy.

Lenders qualify you on the realistic, uncapped tax figure. Budget on it too, not on the seller's bill.

Capped assessment: the tax shock after you buy

Related: Assessed value · Property tax · GDS (gross debt service ratio)

Rates, terms & payments

Cash-back mortgage

A mortgage where the lender pays you a lump sum at closing, set as a percentage of the loan, in exchange for a higher rate for the whole term. Some buyers use it for closing costs or furniture.

The higher rate usually costs more over the term than the cash is worth, and if you break the mortgage early, the lender can claw back some or all of the cash on top of the penalty. Run the arithmetic both ways first.

Related: Closing costs · Prepayment penalty · Interest rate

Buying a home NS

Chattel mortgage

Also called: Chattel financing, Chattel loan

A loan secured against movable property rather than land. In Nova Scotia housing it comes up with mini-homes and mobile homes: a home that is movable and not permanently affixed to the land is eligible under CMHC Chattel Financing, secured by a chattel mortgage.

Fewer lenders write chattel loans, terms are shorter and rates are higher than on an ordinary mortgage. A home permanently affixed to land you own, on a permanent foundation, gets an ordinary mortgage instead.

Mini-home and mobile home financing

Related: Mini-home · Insured mortgage · Subject property

Rates, terms & payments

Closed mortgage

A mortgage you commit to for the full term, where paying it off or changing it early costs a prepayment charge. Most Canadian mortgages are closed, because the rate is meaningfully lower than an open mortgage's.

Closed does not mean frozen. Nearly every closed mortgage lets you prepay a set amount each year without penalty, and many can be ported to a new home.

What breaking a closed mortgage costs

Related: Open mortgage · Prepayment penalty · Prepayment privileges · Porting

Closing & legal NS

Closing costs

Everything you pay on closing day apart from the down payment. In Nova Scotia the largest is municipal deed transfer tax, 1.0% to 1.5% of the price depending on where you buy. Then legal fees, recording fees, title insurance, and adjustments for property tax or fuel the seller prepaid.

They are paid in cash, not added to the mortgage, and lenders check that you have them as well as the down payment.

What closing actually costs in Nova Scotia

Related: Deed transfer tax · Statement of adjustments · Title insurance · Down payment

Closing & legal

Closing date

Also called: Completion date, Possession date

The day ownership and money change hands. The lender sends the mortgage funds to your lawyer, your lawyer pays the seller and registers the deed and mortgage, and the keys follow, usually later the same day.

Pick it with the lender's timeline in mind: your lawyer needs the mortgage instructions several business days before closing, and a rural or construction file takes longer to clear.

Pre-approval to keys: the timeline

Related: Real estate lawyer · Statement of adjustments · Bridge financing · Interest adjustment date (IAD)

Insurance & programs

CMHC

Also called: Canada Mortgage and Housing Corporation

Canada Mortgage and Housing Corporation, the federal Crown corporation that insures mortgages with less than 20% down. Two private insurers, Sagen and Canada Guaranty, do the same job on similar terms; your lender picks which one.

The insurance protects the lender, not you, though you pay the premium. CMHC's limits shape most first-time purchases: a price under $1,500,000, a minimum credit score of 600 for at least one borrower, and debt service ratios of 39% and 44%.

CMHC insurance premium calculator

Related: Mortgage default insurance · Insured mortgage · Down payment · Debt service ratios (GDS and TDS)

Closing & legal

Collateral charge

Also called: Collateral mortgage

A way of registering a mortgage on title for more than you borrow — sometimes up to the full value of the home — so the lender can lend you more later without a new registration.

The convenience has a price. Many lenders will not accept a collateral charge as a straight transfer, so switching at renewal can mean a new registration and legal costs. Ask how your mortgage will be registered before you sign, not when you try to leave.

Related: Standard charge · Switch · Readvanceable mortgage · HELOC (home equity line of credit)

Closing & legal

Commitment letter

Also called: Mortgage commitment, Mortgage approval

The lender's written offer to lend: the amount, rate, term, amortization, payment, and the conditions that must be met before funding. You sign and return it to accept.

Read the conditions list carefully. It is where the lender asks for the documents, appraisal and down payment proof it still needs, and the approval is not firm until every item is signed off.

Related: Conditional approval · Financing condition · Pre-approval · Underwriting

Rates, terms & payments

Comparison rate

The rate your lender measures your mortgage rate against when it works out an interest rate differential. The wider the gap between the two, and the more months left, the bigger the penalty.

There is no single definition. Many large banks use today's posted rate for the term closest to the time you have left, minus the discount you got when you signed; some lenders use their current advertised rate instead. Your mortgage agreement names which.

Mortgage penalty calculator, with each comparison method

Related: Interest rate differential (IRD) · Posted rate · Prepayment penalty · Three months’ interest

Closing & legal

Conditional approval

Also called: Lender conditions

A lender saying yes, subject to proof: an employment letter, recent pay stubs, the down payment history, the appraisal, sometimes an updated credit check. It is a real approval, but it is not money.

Files fall apart at this stage more often than people expect — a down payment that cannot be traced, an appraisal that comes in low. Sending complete documents early is the single best way to get conditions cleared before your financing deadline.

Mortgage documents checklist

Related: Commitment letter · Financing condition · Appraisal · Going firm

Qualifying & credit

Condo fees

Also called: Condominium fees, Common expenses

The monthly amount a condominium owner pays the condominium corporation for shared costs and the reserve fund. Lenders count half of it as a housing cost when they work out your gross debt service ratio.

In Nova Scotia the corporation's estoppel certificate tells your lawyer and lender whether the unit's fees are paid up and whether a special assessment is coming. A corporation that is slow to produce it slows the approval with it.

Related: GDS (gross debt service ratio) · Estoppel certificate · Debt service ratios (GDS and TDS)

Buying a home

Construction mortgage

Also called: Draw mortgage, Progress draw mortgage, Self-build mortgage

Financing for a home that is not built yet. The lender releases the money in stages, called draws, as the build reaches agreed milestones, with an inspection before each one. You pay interest only on what has been advanced so far.

It is a different product from a purchase mortgage: you usually fund the land and early costs first, and a builder's lien holdback applies to each draw. A lender that writes these regularly makes the build far smoother than one that only technically offers them.

Construction mortgages in Nova Scotia

Related: Holdback · Lien · Purchase plus improvements · Appraisal

Qualifying & credit

Consumer proposal

A legally binding deal, filed through a Licensed Insolvency Trustee, to repay creditors part of what you owe instead of declaring bankruptcy. It damages your credit and stays on your report for years after it is paid.

It does not end your chances of a mortgage. Lenders generally want the proposal fully paid and new credit reporting cleanly since; some alternative lenders will lend while it is still being paid, at a higher rate.

Mortgages after a consumer proposal

Related: Bankruptcy · Credit score · B lender · Private mortgage

Insurance & programs

Conventional mortgage

Also called: Low-ratio mortgage, Uninsured purchase

A mortgage with a down payment of 20% or more, so no default insurance is required and no premium is paid.

The surprise is that a conventional borrower can be offered a slightly higher rate than someone with 5% down, because an insured mortgage carries almost no risk for the lender. Skipping the premium usually still wins, but it is worth running both numbers rather than assuming.

Related: Insured mortgage · Insurable mortgage · Uninsured mortgage · Down payment

Qualifying & credit

Co-signer

Also called: Co-borrower

Someone who goes on the mortgage with you, and usually on title, so that their income and credit count toward qualifying. They are fully responsible for the debt if you stop paying.

It is often a parent helping a first-time buyer. The mortgage shows on their credit report and reduces what they can borrow themselves, so agree in writing how and when they come off it.

Related: Guarantor · Debt service ratios (GDS and TDS) · Credit score · First-time home buyer

Qualifying & credit

Credit report

Also called: Credit bureau, Credit check, Equifax, TransUnion

Your borrowing history as recorded by Canada's two main credit bureaus, Equifax and TransUnion: every card, loan and line of credit, its limit and balance, whether you paid on time, and who has checked your credit recently.

Lenders pull it with your permission at pre-approval. You can get your own report from either bureau free, and it is worth doing before you apply so an old error or a forgotten account is not a surprise.

Related: Credit score · Pre-approval · Consumer proposal

Qualifying & credit

Credit score

Also called: Beacon score, Credit rating, FICO score

A three-digit summary of your credit report; in Canada scores usually range from 300 to 900. The minimum for an insured mortgage is 600 for at least one borrower; Nova Scotia's First-time Homebuyers Program asks for 630 and the Down Payment Assistance Program 650. Lenders set their own lines above these.

What moves a score is not mysterious: pay every account on time, and keep card balances well below their limits.

Related: Credit report · B lender · Consumer proposal · Pre-approval

Lenders & brokers NS

Credit union

A member-owned financial institution. Nova Scotia's credit unions are provincially regulated, so the federal stress test rule for uninsured mortgages does not bind them directly; each sets its own qualifying policy, and many use a similar test.

They matter in Nova Scotia for another reason: the provincial First-time Homebuyers Program is delivered only through participating credit unions.

The Nova Scotia First-time Homebuyers Program

Related: A lender · Federally regulated lender · Stress test · First-time Homebuyers Program (Nova Scotia)
Mortgage terms starting with D

Equity, refinancing & renewal

Debt consolidation

Rolling high-interest debt — credit cards, car loans, lines of credit — into your mortgage, usually by refinancing up to 80% of your home's value. The combined monthly payment often drops sharply, because the debt moves to a mortgage rate.

The risk is time. Spreading a five-year car loan over 25 years can cost more in total interest. Keep paying roughly what you paid before and direct the difference at the mortgage.

Debt consolidation mortgages

Related: Refinance · TDS (total debt service ratio) · Second mortgage · Equity

Qualifying & credit

Debt service ratios (GDS and TDS)

Also called: Debt service ratio, Debt-to-income ratio, DSR

The two percentages that decide how much you can borrow. Gross debt service (GDS) is your housing costs against your gross income; total debt service (TDS) adds every other debt payment you carry. On insured mortgages the limits are 39% and 44%, calculated at the stress-test rate, not your actual rate.

When a lender says no, these two numbers are usually why. Paying off a car loan before you apply can move TDS enough to change the answer.

What your income qualifies for

Related: GDS (gross debt service ratio) · TDS (total debt service ratio) · Stress test · Mortgage qualification

Closing & legal

Deed

Also called: Warranty deed, Conveyance

The legal document that transfers ownership of the property from the seller to you. Your lawyer prepares or reviews it and registers it in the Nova Scotia land registration system on closing day, at the same time as your mortgage.

Once registered, the deed is what puts your name on title.

Related: Title · Real estate lawyer · Parcel migration · Deed transfer tax

Closing & legal NS

Deed transfer tax

Also called: Land transfer tax, DTT

Nova Scotia's version of a land transfer tax, set by each municipality: 1.0% to 1.5% of the purchase price across all 49 municipalities. Halifax Regional Municipality charges 1.5%.

It is paid in cash on closing day, through your lawyer, and it cannot be added to the mortgage. Buyers who are not residents may also owe the provincial non-resident deed transfer tax on top.

Deed transfer tax for all 49 municipalities

Related: Closing costs · Non-resident deed transfer tax · Real estate lawyer

Equity, refinancing & renewal

Default

Also called: Mortgage default

Breaking the terms of your mortgage — almost always by missing payments, though letting the home insurance lapse or falling behind on property tax counts too.

One missed payment is not foreclosure. What matters is what you do next: lenders have far more room to help in week two than in month six, through deferrals, a longer amortization or a payment plan. Call them before the second payment is missed.

Related: Arrears · Foreclosure · Mortgage default insurance

Buying a home

Deposit

The money you hand over when your offer is accepted, held in trust — usually by the listing brokerage — until closing. It shows the seller you are serious.

It is not an extra cost: it counts toward your down payment on closing day. It is at risk, though, if you back out after going firm. The lender will want to see where it came from, like the rest of the down payment.

Related: Down payment · Agreement of purchase and sale · Going firm

Closing & legal

Discharge

Also called: Mortgage discharge

Removing a mortgage from title once it is paid off, or when you move it to another lender. The lender signs the discharge and your lawyer registers it.

Most lenders charge a discharge fee, and a switch to a new lender can trigger one even with no penalty. It is one of the small costs worth asking about when you compare a renewal offer with a switch.

Related: Switch · Prepayment penalty · Collateral charge · Title

Buying a home

Down payment

Your own money going into the purchase. The federal minimum is 5% of the first $500,000 and 10% of the remainder (1–2 units); at $1,500,000 and above, insurance is not available and the minimum is 20%. On a rental you will not live in, it is 20%.

Where it comes from matters as much as how much. Lenders want 90 days of statements showing it, a signed gift letter for gifted funds, and records for RRSP or FHSA withdrawals. Nova Scotia's First-time Homebuyers Program allows as little as 2%.

Minimum down payment and CMHC premium calculator

Related: Gift letter · Mortgage default insurance · Down Payment Assistance Program (DPAP) · First Home Savings Account (FHSA)

Insurance & programs NS

Down Payment Assistance Program (DPAP)

Also called: DPAP, Nova Scotia down payment assistance

A Nova Scotia program that lends first-time buyers up to 5% of the price as an interest-free loan, repaid over 10 years. Households need income under $145,000 and credit of 650 or better.

Price caps vary by area: $570,000 in HRM and East Hants, $375,000 in West Hants, the Annapolis Valley and the South Shore, and $300,000 elsewhere. You need an insured pre-approval first; processing takes about 3 weeks.

The Down Payment Assistance Program, in full

Related: First-time Homebuyers Program (Nova Scotia) · Down payment · First-time home buyer · Pre-approval
Default insurance see Mortgage default insurance Draw see Construction mortgage

Mortgage terms starting with E

Equity, refinancing & renewal

Equity

Also called: Home equity

What your home is worth minus everything you owe against it. It grows as you pay down principal and as the market rises.

Equity only becomes usable money when a lender agrees to lend against it: up to 80% of the home's value on a refinance, 65% on a stand-alone home equity line of credit, or 80% when a HELOC and a mortgage share the property. A second mortgage is the usual route past those limits.

HELOCs and home equity

Related: HELOC (home equity line of credit) · Refinance · Second mortgage · Loan-to-value (LTV)

Closing & legal NS

Estoppel certificate

Also called: Condo status certificate

A statement from a Nova Scotia condominium corporation about a particular unit: whether its fees are paid, the corporation's budget and reserve fund, any special assessments, and any legal action under way. Ontario calls it a status certificate.

Your lawyer and lender both rely on it. Ask for it, with the reserve fund study and recent minutes, as early as the agreement allows.

Related: Condo fees · Real estate lawyer · Conditional approval

Equity take-out see Refinance

Mortgage terms starting with F

Lenders & brokers

Federally regulated lender

Also called: FRFI

A bank, or a federally incorporated trust or insurance company, supervised by OSFI. These lenders must apply OSFI's minimum qualifying rate — the stress test — to uninsured mortgages, and follow federal disclosure rules on penalties and the cost of borrowing.

The distinction matters at renewal: a straight switch between two federally regulated lenders is exempt from the stress test.

Related: OSFI · Stress test · Credit union · Switch

Buying a home

Financing condition

Also called: Subject to financing, Mortgage condition

A clause in your offer that lets you walk away, deposit returned, if you cannot arrange a mortgage by a set date. It is your protection while the lender verifies your file and the property.

Give it enough days. A city purchase with a strong pre-approval can clear quickly; a rural Nova Scotia home with a well, septic and few comparable sales needs a longer window for the appraisal and water test.

How long mortgage approval takes

Related: Going firm · Conditional approval · Pre-approval · Well and septic

Insurance & programs

First Home Savings Account (FHSA)

Also called: FHSA, Tax-free first home savings account

A registered account for first-time buyers. Contributions are tax-deductible like an RRSP, and a qualifying withdrawal for a home comes out tax-free like a TFSA. You can put in $8,000 a year, to a $40,000 lifetime limit.

You can use it alongside the Home Buyers' Plan on the same purchase. If you are a year or more from buying and qualify, opening one early is rarely a mistake.

The FHSA: limits, carry-forward and withdrawals

Related: Home Buyers’ Plan (HBP) · Down payment · First-time home buyer · Home Buyers’ Amount

Insurance & programs

First-time home buyer

Also called: First-time buyer, FTHB

There is no single definition; each program sets its own. For Nova Scotia's First-time Homebuyers Program it means no home owned in the last four years. The FHSA and the Home Buyers' Plan use their own four-year lookbacks too, so someone who owned years ago and has rented since may qualify again.

First-time buyers can also take a 30-year amortization on an insured mortgage and claim the $10,000 Home Buyers' Amount on their tax return.

Who counts as a first-time buyer, program by program

Related: First-time Homebuyers Program (Nova Scotia) · Down Payment Assistance Program (DPAP) · First Home Savings Account (FHSA) · Home Buyers’ Plan (HBP)
Insurance & programs NS

First-time Homebuyers Program (Nova Scotia)

Also called: Nova Scotia First-time Homebuyers Program, FTHB pilot, 2% down program

A provincial pilot launched February 3, 2026 that lets first-time buyers put down 2% to 4% with no mortgage insurance premium; the province guarantees 90% of any shortfall instead.

Household income must be under $200,000, credit 630 or better, and the price under $570,000 in HRM and East Hants or $500,000 elsewhere. It runs through participating credit unions only, at a rate capped at prime + 2%.

The 2% down pilot: who qualifies and where

Related: Down Payment Assistance Program (DPAP) · Credit union · First-time home buyer · Mortgage default insurance

Rates, terms & payments

Fixed rate

Also called: Fixed-rate mortgage

A rate locked for the whole term, so your payment is the same from the first month to the last. You pay a little for that certainty, and if rates fall you cannot follow them down without breaking the mortgage — usually the most expensive way to break one.

Fixed rates follow Government of Canada bond yields rather than the Bank of Canada's rate. The real choice between fixed and variable is less about forecasts than about how much a moving payment would bother you.

Related: Variable rate · Interest rate differential (IRD) · Mortgage term · Bank of Canada policy rate

Equity, refinancing & renewal NS

Foreclosure

Also called: Foreclosure and sale

The legal process a lender uses to take and sell a property after a borrower defaults. In Nova Scotia it runs through the Supreme Court of Nova Scotia and ends in a public sale — a slower, court-supervised process than the power of sale used in Ontario, with more room to catch up along the way.

It is the last step, not the first. Deferrals, a refinance, a second mortgage or a planned sale are usually all still possible when someone acts early.

Related: Default · Power of sale · Arrears · Private mortgage

Mortgage terms starting with G

Qualifying & credit

GDS (gross debt service ratio)

Also called: Gross debt service ratio, GDS ratio

The share of your gross monthly income that goes to housing: the mortgage payment, property tax, heating and half of any condo fee. The insured limit is 39%, calculated at the stress-test rate.

It is why two people with the same income can qualify for very different prices: a home with high property tax or a large condo fee uses up the ratio faster.

Affordability calculator

Related: TDS (total debt service ratio) · Debt service ratios (GDS and TDS) · Condo fees · Stress test

Buying a home

Gift letter

Also called: Gifted down payment

A signed letter from an immediate family member confirming that money they gave you for the down payment is a true gift that never has to be repaid. Lenders require it because a hidden loan would change your debt ratios.

The letter is not enough on its own. The lender will also want to see the money land in your account before closing.

Related: Down payment · Co-signer · Conditional approval

Buying a home

Going firm

Also called: Waiving conditions, Firm offer, Subject removal

Removing the conditions from your offer — financing, inspection, well water and so on — so the deal becomes binding. From then on, walking away can cost you the deposit and more.

Go firm on financing only once the lender has signed off the conditions in your commitment, not on the strength of a pre-approval alone.

Related: Financing condition · Deposit · Commitment letter · Agreement of purchase and sale

Insurance & programs

GST/HST new housing rebate for first-time buyers

Also called: First-time home buyers’ GST rebate, FTHB GST rebate

A federal rebate of up to $50,000 of the GST or the federal part of the HST on a newly built home for first-time buyers. The full rebate applies up to $1,000,000, phasing out to nothing at $1,500,000.

It matters on new construction and builder purchases, where the tax is part of the price. Ask your builder and lawyer how it is being applied.

GST/HST rebates on a new home in Nova Scotia

Related: First-time home buyer · Construction mortgage · Closing costs

Qualifying & credit

Guarantor

Someone who promises to cover your mortgage payments if you do not, without owning any part of the home. Fewer lenders accept a guarantor than a co-signer, and many files that start with one end up structured with a co-signer instead.

For insured mortgages, a guarantor's credit can count toward the minimum score requirement. The obligation is real, so they should take independent legal advice before signing.

Related: Co-signer · Credit score · Debt service ratios (GDS and TDS)

Mortgage terms starting with H

Equity, refinancing & renewal

HELOC (home equity line of credit)

Also called: Home equity line of credit, Secured line of credit

A revolving line of credit secured against your home: draw on it, pay it back, draw again. It is usually priced at a margin over prime, and the minimum payment is often interest only.

It can reach 65% of your home's value on its own, or 80% combined with a mortgage. Its flexibility is also its risk: a balance that is never paid down can sit for years.

HELOCs in Nova Scotia

Related: Readvanceable mortgage · Prime rate · Equity · Interest-only payments

Buying a home

Holdback

Money a lender or a lawyer keeps back until something is finished. On a construction mortgage, a portion of each draw is held back for the lien period so unpaid trades can be paid. On a purchase plus improvements mortgage, the renovation money is held until the work is done and inspected.

Plan for it: you or your builder fund the work first and the holdback is released afterwards.

Related: Construction mortgage · Purchase plus improvements · Lien

Insurance & programs

Home Buyers’ Plan (HBP)

Also called: HBP, RRSP Home Buyers’ Plan

A federal program that lets a first-time buyer withdraw up to $60,000 from their RRSP toward a home without paying tax on it, as long as it is paid back to the RRSP. Under the current rules, repayment starts in the fifth year after the withdrawal year for withdrawals made 2026–2028, over 15 years.

It can be combined with an FHSA on the same purchase. A missed repayment is added to your income for that year.

The Home Buyers’ Plan: limit, repayment and grace period

Related: First Home Savings Account (FHSA) · Down payment · First-time home buyer

Buying a home

Home inspection

A buyer's own check of the property's condition — roof, foundation, wiring, plumbing, heating — by a home inspector, usually written into the offer as a condition. It is for you, not the lender, and it is different from the appraisal.

In Nova Scotia it is also where older-home issues surface that can affect insurance and the mortgage: the age and tag of an oil tank, a wood stove without a WETT inspection, or a well and septic that need their own tests.

Oil tanks, wells and wood heat

Related: Appraisal · Oil tank · WETT inspection · Well and septic

Closing & legal

Home insurance

Also called: Property insurance, Fire insurance

Insurance on the building itself. Every lender requires it, with the lender named on the policy, before the mortgage funds — and it is a different product from mortgage default insurance and mortgage life insurance.

In Nova Scotia, insurers set their own rules on oil tanks, wood heat and older wiring, and an uninsurable property is an unmortgageable one. Get a quote before you go firm, not the week of closing.

Related: Oil tank · WETT inspection · Mortgage default insurance · Mortgage life insurance

High-ratio mortgage see Insured mortgage

Mortgage terms starting with I

Insurance & programs

Insurable mortgage

A mortgage with 20% or more down that still meets every insurer rule — a price under $1,500,000, an amortization of 25 years or less, owner-occupied, a purchase or a switch rather than a refinance. The lender can insure it in bulk at its own cost.

You never see the insurance, but you often see the better rate. It is the middle of three pricing tiers: insured, insurable, uninsured.

Related: Insured mortgage · Uninsured mortgage · Conventional mortgage · Mortgage default insurance

Insurance & programs

Insured mortgage

Also called: High-ratio mortgage, CMHC-insured mortgage

A mortgage with less than 20% down, where default insurance is required and the premium — 2.8% to 4% of the mortgage depending on your down payment — is added to the balance.

You pay for the insurance and the lender is the one protected. The upside: because the lender carries almost no risk, insured mortgages usually get the lowest rates available.

CMHC premium at every down payment

Related: Mortgage default insurance · CMHC · Insurable mortgage · Down payment

Closing & legal

Interest adjustment date (IAD)

Also called: IAD, Interest adjustment

The date your regular payment schedule officially starts. If you close mid-month, the lender charges interest for the days between closing and that date — either taken from the mortgage advance on closing day or collected as a separate first payment.

It is not a fee, just interest for real days, but it surprises people when the lawyer's statement shows it.

Related: Closing date · Statement of adjustments · Payment frequency

Rates, terms & payments

Interest rate

Also called: Mortgage rate, Contract rate

The yearly cost of borrowing, as a percentage of what you owe. Canadian fixed-rate mortgages are compounded semi-annually, not in advance, which is written into every Canadian mortgage and makes the true cost a touch lower than a monthly-compounded rate of the same number.

The rate is only part of the price. Prepayment privileges, the penalty formula, portability and how the mortgage is registered decide what it really costs over the term.

Nova Scotia mortgage rates

Related: Fixed rate · Variable rate · Annual percentage rate (APR) · Posted rate

Equity, refinancing & renewal

Interest rate differential (IRD)

Also called: IRD, IRD penalty

The penalty formula for breaking a fixed-rate mortgage early. It is the interest rate differential: the lender works out the interest left to pay on the remaining term at your rate, works it out again at a comparison rate, and charges the difference. The comparison rate is either the posted rate for a term of similar length, or that posted rate less the discount you were originally given — which one a lender uses is set out in the mortgage contract, and the two produce very different numbers.

In the Financial Consumer Agency of Canada's own example, three months' interest is $3,000 and the IRD is $12,000 on the same mortgage. Get the figure in writing from your lender before you plan anything around it.

Breaking your mortgage, and the penalty maths

Related: Comparison rate · Three months’ interest · Prepayment penalty · Posted rate

Mortgage terms starting with L

Lenders & brokers

Lender

Also called: Mortgage lender, Mortgagee

The institution or person that advances the money and holds the mortgage — a bank, credit union, monoline, trust company, mortgage investment corporation or private individual. Each has its own appetite for different files, and its own rates.

A broker's job is to match your file to the lender that reads it best, rather than the one you happen to bank with.

The lenders available in Nova Scotia

Related: A lender · B lender · Monoline lender · Private mortgage

Closing & legal

Lien

Also called: Builder’s lien, Judgment, Encumbrance

A legal claim registered against a property for money owed — a mortgage, an unpaid contractor (a builder's lien), a court judgment, or the Canada Revenue Agency. Liens must be cleared before a property can be sold or refinanced cleanly.

They surface in your lawyer's title search whether you remember them or not. An old lien nobody discharged is a classic closing-week problem.

Related: Title · Holdback · Arrears · Title insurance

Qualifying & credit

Loan-to-value (LTV)

Also called: LTV, Loan-to-value ratio

Your mortgage divided by the property's value, as a percentage. Put 20% down and you are at 80% LTV.

It drives almost everything: whether insurance is required, the premium (2.8% at 80.01% to 85%, 4% at 90.01% to 95%), which lenders will look at the file, and how much equity you can borrow later. Every product has an LTV ceiling.

Related: Down payment · Equity · Mortgage default insurance · Appraisal

Land transfer tax see Deed transfer tax Lump-sum prepayment see Prepayment privileges

Mortgage terms starting with M

Equity, refinancing & renewal

Maturity date

Also called: Renewal date, Term end

The day your current term ends and the remaining balance comes due: you renew, switch lenders or pay it off. Start comparing about 4 months before it.

That runway is your leverage. Most lenders hold a rate for 90–120 days, and once the date passes you are usually taking whatever the renewal letter offered.

Mortgage renewal in Nova Scotia

Related: Renewal · Switch · Mortgage term · Rate hold

Buying a home NS

Mini-home

Also called: Mobile home, Manufactured home, Modular home

Nova Scotia's everyday word for a single-section manufactured home. How it is financed depends on how it sits: a home permanently affixed to the land and placed on a permanent foundation is eligible under standard underwriting, secured by an ordinary mortgage, insured up to 95% of value under CMHC Prefab Plus with a minimum credit score of 600.

A home on a rented lot or one that can be moved is chattel financing instead — fewer lenders, shorter terms, higher rates.

Mini-home and mobile home mortgages

Related: Chattel mortgage · Insured mortgage · Down payment

Buying a home

MLS® listing

Also called: MLS, Multiple Listing Service, MLS number

The listing a REALTOR® publishes on the shared Multiple Listing Service, and the source of what you see on REALTOR.ca. Its MLS® number identifies the property for your lender and appraiser.

Lenders ask for a copy of the listing with your offer. A private sale with no listing is fine, but expect the lender to look at the property and the price a little harder.

Related: Agreement of purchase and sale · Appraisal · Subject property

Lenders & brokers

Monoline lender

A lender whose business is mortgages: no branches, no chequing accounts, and usually reached only through a mortgage broker. "Monoline" describes the business model, not the borrower: most well-known monolines are prime A lenders working to the same insurance rules as the banks, and some also run a separate alternative line.

They take no deposits, and most are licensed provincially rather than supervised by OSFI. If one is sold or fails, your mortgage contract carries on with whoever holds or services it.

Monoline lenders vs banks

Related: A lender · Mortgage broker · Lender

Lenders & brokers

Mortgage

Also called: Charge, Mortgagor, Mortgagee

A loan secured against real property. If you do not repay, the lender can enforce the security through the courts. You, the borrower, are the mortgagor; the lender is the mortgagee — the names people mix up most.

Every mortgage has a principal, a rate, a term and an amortization, and is registered on the property's title until it is discharged.

Related: Principal · Mortgage term · Amortization · Discharge

Lenders & brokers

Mortgage broker

Also called: Mortgage agent, Mortgage specialist, Mortgage advisor

A licensed professional who arranges your mortgage with whichever lender suits your file, rather than selling one institution's products. A broker can reach banks, credit unions, monoline lenders, and alternative and private lenders through one application.

On a standard residential mortgage the lender pays the broker, not you. In Nova Scotia the licence classes are mortgage broker and associate mortgage broker, working through a licensed brokerage. A bank's "mortgage specialist" is an employee of that bank, not a broker.

Mortgage broker or bank?

Related: Associate mortgage broker · Mortgage brokerage · Broker fee · Monoline lender

Lenders & brokers NS

Mortgage brokerage

The licensed firm that brokers and associate brokers work under. In Nova Scotia the brokerage holds its own licence, is responsible for its licensees, and must give you written disclosures about fees and any relationship with a lender.

Oickle Mortgages works under Indi, The Independent Mortgage Company Ltd., Nova Scotia Mortgage Brokerage licence 3000688.

Disclosure and licensing

Related: Mortgage broker · Associate mortgage broker · Broker fee

Insurance & programs

Mortgage default insurance

Also called: Mortgage loan insurance, CMHC insurance, Default insurance, Sagen, Canada Guaranty

Insurance that repays the lender if the borrower defaults, required whenever the down payment is under 20%. It is provided by CMHC, Sagen or Canada Guaranty.

The premium is a percentage of the mortgage that rises with the loan-to-value: 2.4% at 75.01% to 80%, 2.8% at 80.01% to 85%, 3.1% at 85.01% to 90% and 4% at 90.01% to 95%. It is added to the mortgage, and Nova Scotia charges no sales tax on it.

CMHC insurance calculator

Related: CMHC · Insured mortgage · Loan-to-value (LTV) · Mortgage life insurance

Insurance & programs

Mortgage life insurance

Also called: Creditor insurance, Mortgage protection insurance

Optional insurance, usually offered by the lender, that pays off the mortgage if you die (some versions also cover disability or critical illness). The lender is the beneficiary and the payout shrinks with the balance.

It is often underwritten when you claim rather than when you sign, which can leave a family surprised. A personal term life policy of the same size is frequently cheaper, pays your family, and goes with you if you change lenders. Talk to a licensed insurance advisor before you tick the box.

Related: Mortgage default insurance · Home insurance

Qualifying & credit

Mortgage qualification

Also called: Qualifying for a mortgage, Affordability

How a lender decides how much it will lend. Four things are checked: income (verified, and averaged over two years if self-employed), debts (through the GDS and TDS ratios at the stress-test rate), credit (insured files need 600 or better), and the down payment and closing costs, with a traceable source.

The property is checked too. A strong borrower on a property the lender will not accept is still a decline.

See what you qualify for

Related: Debt service ratios (GDS and TDS) · Stress test · Credit score · Pre-approval

Rates, terms & payments

Mortgage term

Also called: Term

How long your current contract with the lender lasts — anywhere from a few months to several years. At the end of the term the remaining balance does not disappear; you renew it, switch it or pay it off.

Term is the commitment window; amortization is the whole road. Keeping those two straight answers most of the questions people arrive with.

Related: Amortization · Maturity date · Renewal · Fixed rate

Minimum qualifying rate see Stress test Mortgage penalty see Prepayment penalty

Mortgage terms starting with N

Insurance & programs

New-to-Canada mortgage

Also called: Newcomer mortgage, Newcomers program

Insured mortgage options for permanent and non-permanent residents who have not yet built a Canadian credit history. Under CMHC's newcomers criteria you can buy with 5% down on one or two units; non-permanent residents must be legally authorised to work in Canada, for example on a work permit.

Where Canadian credit is thin, lenders can accept an international credit report, a letter of reference from the borrower’s financial institution in their country of origin, or other alternative methods of establishing creditworthiness.

Mortgages for newcomers to Canada

Related: Non-resident mortgage · Credit report · Insured mortgage

Closing & legal NS

Non-resident deed transfer tax

Also called: NRDTT, Non-resident land transfer tax

A provincial tax of 10% on Nova Scotia residential property with three dwelling units or fewer, including residential vacant land, charged on the higher of the purchase price and the assessed value, when the buyer is not a Nova Scotia resident. It is on top of the municipal deed transfer tax.

You are exempt if you move here and make the home your primary residence. The province has extended the window to prove residency to one year (extended from six months, announced 7 August 2026).

Non-resident deed transfer tax, explained

Related: Deed transfer tax · Non-resident mortgage · Assessed value · Closing costs

Qualifying & credit

Non-resident mortgage

Also called: Foreign buyer mortgage

Financing for someone who does not live in Canada for tax purposes, whether a Canadian working abroad or a foreign national. Expect a larger down payment than a resident, more paperwork to verify foreign income and credit, and fewer lenders willing to look.

A temporary federal ban also stops most non-Canadians from buying residential property, with exemptions. In Nova Scotia, the non-resident deed transfer tax applies on top.

Related: Non-resident deed transfer tax · New-to-Canada mortgage · Down payment

Qualifying & credit

Notice of Assessment (NOA)

Also called: NOA, T1 General, T4

The statement the Canada Revenue Agency sends after it processes your tax return, showing your income and whether you owe anything. Lenders use it to confirm income and to check that no taxes are outstanding.

Self-employed borrowers usually need two years of Notices of Assessment with the matching T1 General returns; salaried borrowers more often give T4 slips, recent pay stubs and an employment letter.

Mortgage documents checklist

Related: Self-employed mortgage · Arrears · Mortgage qualification

Mortgage terms starting with O

Buying a home NS

Oil tank

Also called: Heating oil tank, Oil tank tag

Many Nova Scotia homes still heat with oil, and the tank matters at closing because home insurers set rules on its age and condition. Nova Scotia itself sets no service-life limit; the limits are the insurers', and they do not publish them.

The tank should be installed to CSA B139, Installation Code for Oil-Burning Equipment, and the National Fire Code of Canada by a trained and licensed oil burner technician, and the metal tag or label on the tank carries the manufacturing standard and the year of manufacture — it should never be painted over. No insurance means no mortgage, so check the tag before you go firm.

Oil tanks, wells and wood heat

Related: Home insurance · Home inspection · WETT inspection · Well and septic

Rates, terms & payments

Open mortgage

A mortgage you can pay off in full, or in part, at any time with no penalty, in exchange for a noticeably higher rate.

It fits a short list of situations: you are selling within months, expecting a large lump sum, or need a few months' flexibility before a longer commitment. For anyone keeping the mortgage for years, the higher rate costs far more than a penalty would.

Related: Closed mortgage · Prepayment penalty · Variable rate

Buying a home

Opportunity cost

Also called: Opportunity cost of a down payment

What money could have earned if you had used it another way. A down payment is not spent the way rent is, because it comes back as equity, but while it sits in a house it is not invested anywhere else.

That is why a fair rent-or-buy comparison has the renter invest the cash the buyer puts into the down payment and closing costs, and compares what each ends up with rather than the monthly payments.

Rent vs buy calculator for Halifax

Related: Down payment · Equity · Closing costs

Lenders & brokers

OSFI

Also called: Office of the Superintendent of Financial Institutions, B-20

The Office of the Superintendent of Financial Institutions, the federal regulator of banks and other federally regulated lenders. Its Guideline B-20 sets their mortgage underwriting standards, including the minimum qualifying rate on uninsured mortgages: the greater of the contract rate plus 2% and 5.25%.

Since November 21, 2024, OSFI exempts a straight switch of an uninsured mortgage between federally regulated lenders from that test.

Related: Stress test · Federally regulated lender · Switch · Uninsured mortgage

Buying a home

Owner-occupied

A property you will live in as your home. It changes the rules: owner-occupied homes of one to four units can be insured with as little as 5% down on one or two units and 10% on three or four, while a rental you will not live in needs 20% down.

Living in one unit of a duplex and renting the other counts as owner-occupied, and CMHC lets up to 100% of the other unit's rent count toward your income.

Investment property mortgages, 1 to 4 units

Related: Rental income · Down payment · Insured mortgage

Mortgage terms starting with P

Closing & legal NS

Parcel migration

Also called: Migration, Land Registration Act migration, Migrated title

Nova Scotia moved property records from the old registry of deeds into a land registration system that guarantees title. A parcel that has not changed hands since must be "migrated" into the new system the first time it is sold or mortgaged.

Migration is your lawyer's job, but it takes extra work — a title search back through older records — so it can add time and cost to a closing on an older rural property.

Related: PID (parcel identifier) · Title · Real estate lawyer · Deed

Closing & legal NS

PID (parcel identifier)

Also called: PID, Parcel identification number

The unique number Nova Scotia gives each parcel of land. Lawyers, lenders, appraisers and the assessment office all use it to identify the property exactly, so it appears on the agreement, the appraisal and the mortgage.

If you are buying land with more than one PID, make sure every one is in the offer and the lender's instructions.

Related: Parcel migration · Title · Assessed value

Equity, refinancing & renewal

Porting

Also called: Portable mortgage, Port

Taking your existing mortgage — rate, balance and remaining term — to a new home when you sell and buy, so you avoid a penalty mid-term.

The rules are tighter than people expect: the lender re-approves you and the new property, the two closings must fall within the lender's window, and if you need more money the extra is usually blended at today's rate.

Related: Blend and extend · Prepayment penalty · Bridge financing · Closed mortgage

Rates, terms & payments

Posted rate

The rate a bank advertises before any discount — the chartered banks' five-year posted rate was 6.09% for the week of September 16, 2026, as reported to the Bank of Canada. Almost nobody pays it.

It matters because some lenders use the posted rate in their penalty formula. If your discount was large, an IRD calculated against posted rates can be much bigger than you expected.

Nova Scotia mortgage rates

Related: Interest rate differential (IRD) · Interest rate · Prime rate

Equity, refinancing & renewal

Power of sale

A way for a lender to sell a defaulted property without a court order, used in Ontario and some other provinces. It is not how Nova Scotia works: here a lender has to go through foreclosure in the Supreme Court of Nova Scotia.

If you read about power of sale online, check which province the writer is in.

Related: Foreclosure · Default

Qualifying & credit

Pre-approval

Also called: Mortgage pre-approval, Rate hold

A lender or broker reviewing your income, credit and down payment and giving you a maximum price, usually with a held rate. It takes 1–3 business days once documents are in, and the rate is typically held for 90–120 days.

It is not a final approval: the property still has to pass, and your documents are re-checked once you have an accepted offer. It is still the step that turns house hunting into a real number.

Mortgage pre-approval in Nova Scotia

Related: Pre-qualification · Rate hold · Commitment letter · Mortgage qualification

Equity, refinancing & renewal

Prepayment penalty

Also called: Prepayment charge, Mortgage penalty, Breaking a mortgage

What you pay to break a closed mortgage early. On a variable rate it is usually an amount equal to three months’ interest on what you still owe. On a fixed rate it is usually the greater of that and the interest rate differential, which can be far larger.

Your lender must give you the figure, how it was calculated and how long it is valid when you ask. Lenders may also charge administration fees, appraisal fees, reinvestment fees and a mortgage discharge fee.

Breaking your mortgage: the real cost

Related: Interest rate differential (IRD) · Prepayment privileges · Closed mortgage · Porting

Rates, terms & payments

Prepayment privileges

Also called: Lump-sum prepayment, Payment increase, Double-up payments

The extra payments your contract lets you make each year without penalty — typically an annual lump sum up to a set percentage of the original balance, and the right to raise your regular payment. The amounts are set out in a single information box in your mortgage agreement.

They are valuable and widely ignored. Every extra dollar goes to principal, and the earlier in the amortization it goes in, the more interest it saves.

Related: Prepayment penalty · Principal · Accelerated bi-weekly payments · Closed mortgage

Rates, terms & payments

Prime rate

Also called: Prime, Bank prime rate

The benchmark rate the banks set for variable lending, which moves with the Bank of Canada's policy rate. Chartered-bank prime was 4.45% for the week of September 16, 2026.

Variable mortgages and HELOCs are quoted against it, as "prime minus" or "prime plus" a margin. When prime moves, your rate moves the same day; your payment or your amortization moves with it.

Nova Scotia mortgage rates today

Related: Bank of Canada policy rate · Variable rate · HELOC (home equity line of credit) · Trigger rate

Rates, terms & payments

Principal

Also called: Principal balance

The amount you borrowed and still owe, as opposed to the interest charged on it. Each blended payment splits between the two, and early on the split leans heavily to interest.

That is why a prepayment in year two does far more than the same amount in year twenty: it removes principal that would otherwise collect interest for decades.

Related: Blended payment · Interest rate · Prepayment privileges · Amortization

Lenders & brokers

Private mortgage

Also called: Private lender, Private lending, MIC, Mortgage investment corporation

A loan from an individual investor or a mortgage investment corporation rather than a bank, credit union or B lender. It is approved mainly on the property's equity, not your income or credit, so it can close files nobody else will.

Rates and fees are well above bank pricing and terms are short, often a year. A private mortgage is a bridge to somewhere — it only makes sense with a dated plan for getting out of it.

Private mortgage lenders in Nova Scotia

Related: B lender · Second mortgage · Broker fee · Annual percentage rate (APR)

Qualifying & credit

Property tax

Also called: Municipal tax

The annual tax your municipality charges, based on the PVSC assessed value. Lenders count it in your gross debt service ratio, and some collect it with your mortgage payment and pay it for you.

In Nova Scotia, budget on the uncapped figure: the capped assessment usually comes off after a sale, and the bill can rise the next year.

Related: Assessed value · Capped Assessment Program (CAP) · GDS (gross debt service ratio) · Arrears

Buying a home

Purchase plus improvements

Also called: Purchase plus renovations

A purchase mortgage that includes money for renovations, so you can buy a home that needs work and pay for it at a mortgage rate. The lender bases the loan on the value after the work and holds the renovation money back until the work is done and inspected.

Quotes must be in place before closing, and you or your contractor carry the cost until the holdback is released.

Related: Holdback · Construction mortgage · Appraisal · Insured mortgage

Mortgage terms starting with Q

Qualifying rate see Stress test

Mortgage terms starting with R

Rates, terms & payments

Rate hold

Also called: Rate guarantee, Rate lock

A lender guaranteeing a rate while you shop or renew, typically for 90–120 days depending on the lender. If rates rise you keep the held rate; if they fall you generally get the lower one.

It holds a rate, not an approval of a particular house. There is no cost to it, so being without one while you are actively looking is an unforced error.

Related: Pre-approval · Renewal · Maturity date

Equity, refinancing & renewal

Readvanceable mortgage

Also called: All-in-one mortgage, Mortgage plus HELOC

A mortgage and a home equity line of credit registered together. As you pay down the mortgage, the line's limit grows by the same amount, up to the 80% combined ceiling. At a federally regulated lender, lending above 65% of the home's value amortizes and does not readvance, so the line only grows once the mortgage is below 65%.

It is flexible and useful for planned borrowing, and it is the product the Smith Manoeuvre relies on. It is usually registered as a collateral charge, which makes switching lenders later more involved.

HELOCs and readvanceable mortgages

Related: HELOC (home equity line of credit) · Collateral charge · Equity · Smith Manoeuvre

Closing & legal NS

Real estate lawyer

Also called: Closing lawyer, Solicitor

In Nova Scotia every purchase and mortgage closes through a lawyer. Yours searches and certifies title, migrates the parcel if needed, takes the lender's instructions, holds the money in trust, pays the deed transfer tax, registers the deed and mortgage, and prepares the statement of adjustments.

The lender's instructions usually need to reach your lawyer 5–7 business days before closing, so pick one as soon as your offer is accepted.

Nova Scotia closing costs

Related: Closing date · Statement of adjustments · Title · Parcel migration

Equity, refinancing & renewal

Refinance

Also called: Refinancing, Equity take-out, Cash-out refinance

Replacing your mortgage with a new, larger one — or one with a different amortization — and taking the difference in cash, usually for debt consolidation, renovations or an investment. You can borrow up to 80% of the home's value.

A refinance is re-qualified under the stress test and needs an appraisal and a lawyer. Mid-term, it also triggers a penalty, so the saving has to clear that first.

Refinancing in Nova Scotia

Related: Debt consolidation · Equity · HELOC (home equity line of credit) · Second mortgage

Equity, refinancing & renewal

Renewal

Also called: Mortgage renewal

Signing a new term when your current one matures. Your lender mails an offer, and that first offer is very often not its best rate — it is priced on the assumption you will not shop.

Renewal is the easiest place to save on a mortgage. You can renew with your lender, negotiate, or switch to another lender, and a straight switch between federally regulated lenders no longer needs the stress test.

Mortgage renewal and switching

Related: Switch · Maturity date · Rate hold · Refinance

Qualifying & credit

Rental income

Also called: Rental add-back, Rental offset

Rent from a property counted toward qualifying, either added to your income (an add-back) or subtracted from the property's costs (an offset). On an insured, owner-occupied duplex CMHC allows up to 100% of the gross rent; on three or four units, up to 50%.

On an uninsured rental each lender sets its own method and percentage, which is where lender choice makes a real difference.

Investment property mortgages

Related: Owner-occupied · Debt service ratios (GDS and TDS) · Secondary suite refinance

Equity, refinancing & renewal

Reverse mortgage

Also called: CHIP reverse mortgage

A loan for homeowners 55 and older that turns home equity into cash with no regular payments. You can borrow up to 55% of your home's value, and it is repaid on the sale of the home, a permanent move out, the death of the last borrower, or default.

Interest compounds on a growing balance, and rates are above a regular mortgage. It suits some situations well; if your income can carry a payment, compare a HELOC or refinance first.

Reverse mortgages in Nova Scotia

Related: HELOC (home equity line of credit) · Equity · Refinance

Mortgage terms starting with S

Equity, refinancing & renewal

Secondary suite refinance

Also called: Secondary suite financing, Basement apartment refinance

A federal rule, in effect since January 15, 2025, that allows insured refinancing to add a rental suite to a home: up to 90% of the value once the suite is finished, on a property worth under $2,000,000, amortized over up to 30 years, with no more than 4 units in total.

The owner or a close relative must live in one of the units.

Refinancing in Nova Scotia

Related: Refinance · Rental income · Owner-occupied

Qualifying & credit

Self-employed mortgage

Also called: Business-for-self mortgage, BFS

Lenders qualify self-employed income on a two-year average of what you declared to the Canada Revenue Agency, so they want two years of Notices of Assessment and T1 General returns. CMHC recommends at least 24 months in business and allows a 15% gross-up of net income.

If write-offs leave your declared income low, an alternative lender's bank-statement or stated-income program is the other route.

Self-employed mortgages in Nova Scotia

Related: Notice of Assessment (NOA) · Stated income · B lender · Debt service ratios (GDS and TDS)

Equity, refinancing & renewal

Smith Manoeuvre

Also called: Smith Maneuver

A Canadian borrowing-to-invest strategy built on a readvanceable mortgage: as mortgage payments repay principal, the same amount is borrowed back on the HELOC and invested in a non-registered account. Interest on money borrowed to earn investment income may be tax-deductible; interest on your home mortgage is not.

Total debt does not fall, it moves from the mortgage to the investment line, and investment losses do not reduce what you owe. Whether the interest is deductible depends on how the money is used and traced, which is a question for an accountant.

Smith Manoeuvre calculator

Related: Readvanceable mortgage · HELOC (home equity line of credit) · Collateral charge

Equity, refinancing & renewal

Spousal buyout

Also called: Separation buyout, Equity buyout

Buying out a former spouse or partner's share of the home after a separation. Insurer programs treat it as a purchase rather than a refinance, so it is not held to the 80% refinance ceiling.

It needs a fully executed separation agreement setting out the buyout amount, and you must qualify for the whole mortgage on your own income.

Separation and spousal buyout mortgages

Related: Refinance · Mortgage qualification · Equity

Closing & legal

Standard charge

Also called: Conventional charge

A mortgage registered on title for exactly the amount you borrow. To borrow more later you need a new registration, but most lenders will take over a standard charge at renewal as a simple transfer.

It is the opposite of a collateral charge, and usually the easier one to switch.

Related: Collateral charge · Switch · Title

Qualifying & credit

Stated income

Also called: Bank-statement program, Stated income mortgage

An alternative-lender approach for self-employed borrowers whose tax returns understate what the business really earns. The lender looks at bank statements and the business itself to judge whether the stated income is reasonable, and usually wants a larger down payment or more equity.

It costs more than an A-lender mortgage, but it can be the bridge to one once two years of higher declared income are on file.

Self-employed mortgages

Related: Self-employed mortgage · B lender · Notice of Assessment (NOA)

Closing & legal

Statement of adjustments

The lawyer's closing statement showing exactly what changes hands: the price, the deposit already paid, the mortgage advance, and credits back and forth for property tax, fuel oil or condo fees the seller has prepaid or owes.

It is how you learn the exact amount you must bring to your lawyer before closing, so ask for it as early as your lawyer can produce it.

Related: Closing costs · Real estate lawyer · Interest adjustment date (IAD) · Deposit

Qualifying & credit

Stress test

Also called: Minimum qualifying rate, MQR, Qualifying rate

The federal rule that makes you qualify at the greater of the contract rate plus 2% and 5.25%, even though you pay your actual rate. Insured mortgages apply the same test through the insurer.

It is why your approval is smaller than a simple calculation suggests. A straight switch of an uninsured mortgage between federally regulated lenders at renewal is exempt, as long as the balance and amortization do not grow (up to $3,000 can be added for fees).

Mortgage payment and qualifying calculator

Related: Debt service ratios (GDS and TDS) · OSFI · Switch · Mortgage qualification

Buying a home

Subject property

The property a mortgage application is about — the one being bought, refinanced or offered as security. You see the phrase on lender documents and appraisals.

It matters when you own more than one property: the lender assesses the subject property's value, condition and any rental income on its own.

Related: Appraisal · Rental income · Loan-to-value (LTV)

Equity, refinancing & renewal

Switch

Also called: Transfer, Straight switch, Lender switch

Moving your mortgage balance to a new lender at renewal without borrowing more or extending the amortization. The new lender often covers most of the legal and appraisal costs to win the file.

Since November 21, 2024, a straight switch of an uninsured mortgage between federally regulated lenders no longer needs the stress test. A collateral charge can add cost and paperwork.

Renewal savings calculator

Related: Renewal · Stress test · Collateral charge · Discharge

Mortgage terms starting with T

Qualifying & credit

TDS (total debt service ratio)

Also called: Total debt service ratio, TDS ratio

Your housing costs plus every other monthly debt payment — car loans, card minimums, student loans, support payments, lines of credit — against your gross income. The insured limit is 44%, at the stress-test rate.

Paying off a single car loan before applying can move this number enough to change what you qualify for, so review it months ahead, not the week you apply.

Affordability calculator

Related: GDS (gross debt service ratio) · Debt service ratios (GDS and TDS) · Debt consolidation · Stress test

Rates, terms & payments

Three months’ interest

Also called: 3 months interest penalty, Three-month interest penalty

The usual penalty for breaking a closed variable-rate mortgage, and the minimum on most closed fixed-rate ones: the balance being paid off × the annual rate × 3 ÷ 12. On $400,000 at 5.5%, that is $5,500.

It is three months of interest, not three mortgage payments, which would be larger because a payment also repays principal. On a fixed rate, lenders usually charge the greater of this and the interest rate differential.

Mortgage penalty calculator: three months’ interest and IRD

Related: Prepayment penalty · Interest rate differential (IRD) · Variable rate · Closed mortgage

Closing & legal

Title

Also called: Title search, On title

Legal ownership of a property, and the record of every interest registered against it: owners, mortgages, liens and easements. Being "on title" means you are a registered owner.

Before closing, your lawyer searches title to make sure the seller can sell and nothing unexpected is registered against it.

Related: Deed · Lien · Title insurance · Parcel migration

Closing & legal

Title insurance

A one-time policy that protects against problems with title — fraud, errors in the records, survey issues, liens the search missed. Lenders usually require a lender's policy; an owner's policy protects your own equity and is a separate choice.

Ask your lawyer which you are getting, and what it costs, before closing.

Related: Title · Lien · Closing costs · Real estate lawyer

Rates, terms & payments

Trigger rate

Also called: Trigger point

On a variable-rate mortgage with a fixed payment, the rate at which your payment no longer covers the interest. Past it, unpaid interest is added to the balance and the mortgage grows instead of shrinking.

The lender will then ask for a higher payment or a lump sum, especially if the balance reaches the trigger point set in your contract. Know your trigger rate if you hold this kind of variable.

Related: Variable rate · Prime rate · Amortization

Mortgage terms starting with U

Qualifying & credit

Underwriting

Also called: Underwriter

The lender's review of your file: income, credit, debts, down payment and the property, measured against its own guidelines and the insurer's. The underwriter decides whether to approve, decline or approve with conditions.

A broker's work is largely here — presenting the file so the underwriter sees it clearly, and sending it to a lender whose guidelines fit it.

Related: Conditional approval · Commitment letter · Mortgage qualification

Insurance & programs

Uninsured mortgage

A mortgage that cannot be insured at all: a price of $1,500,000 or more, an amortization over 25 years (unless it qualifies for 30), a rental property, or a refinance. The lender carries the full risk, so it is usually the highest-priced of the three tiers.

Most refinances land here, which surprises borrowers who had an insured rate on their purchase.

Related: Insured mortgage · Insurable mortgage · Refinance · Stress test

Mortgage terms starting with V

Rates, terms & payments

Variable rate

Also called: Variable-rate mortgage, Adjustable-rate mortgage, ARM

A rate that moves with your lender's prime rate, quoted as prime plus or minus a margin. Breaking one usually costs an amount equal to three months’ interest on what you still owe, far less than a typical fixed-rate penalty.

There are two kinds. With an adjustable rate the payment changes when prime does; with a fixed-payment variable the payment stays put and the split between interest and principal shifts — which is where trigger rates come in. Know which one you have.

Related: Prime rate · Fixed rate · Trigger rate · Bank of Canada policy rate

Buying a home

Vendor take-back mortgage (VTB)

Also called: VTB, Seller financing

The seller lends you part of the purchase price and takes a mortgage back on the property they just sold you. It shows up in family sales, rural land and properties that conventional lenders find awkward.

Your main lender must agree to it, it is usually registered behind the first mortgage, and the seller should take tax advice before signing.

Related: Second mortgage · Private mortgage · Down payment

Mortgage terms starting with W

Buying a home NS

Well and septic

Also called: Well water test, Septic inspection, Potability test

Much of rural Nova Scotia is on a private well and septic system, and lenders usually want a water potability test, often with a septic inspection, before they fund. Build the time into your financing condition.

The province recommends testing well water for bacteria every six months and for chemistry every two years, and names arsenic and uranium, which Nova Scotia names as prevalent in the province and a health risk.

Oil tanks, wells and wood heat

Related: Financing condition · Home inspection · Oil tank · Appraisal

Buying a home NS

WETT inspection

Also called: WETT, Wood stove inspection, Wood Energy Technology Transfer

An inspection of a wood stove, fireplace insert or chimney by someone certified through WETT (Wood Energy Technology Transfer). Wood heat is common in Nova Scotia, and home insurers often ask for a WETT report before they will cover the house.

No insurance, no mortgage — so if the home has a wood stove, arrange the inspection during your conditions, not after.

Oil tanks, wells and wood heat

Related: Home insurance · Oil tank · Home inspection

Definitions are general information for Canadian residential mortgages, not advice on your file. Figures come from the sources listed on the sources page and were checked on September 20, 2026; the Bank of Canada rates were observed on September 16, 2026.

Quick answers

What is mortgage amortization?

Amortization is the total time it would take to pay your mortgage to zero at your current payment. On an insured mortgage the maximum is 25 years, or 30 for first-time buyers and buyers of a new build. A longer amortization lowers the payment but raises the total interest you pay. See it in the payment calculator →

What is the difference between a mortgage term and amortization?

The term is the length of the contract you sign now, usually a few years; when it ends you renew, switch or pay off the balance. The amortization is the whole time to pay the mortgage off, usually decades. Most people go through several terms in one amortization. What happens when a term ends →

What is a B lender?

A B lender, or alternative lender, approves files the banks decline: hard-to-document self-employed income, bruised credit, a recent consumer proposal, or debt ratios above the standard limits. You pay a higher rate and usually a lender fee, and the plan is normally to move back to an A lender at renewal. B-lenders and alternative lending →

What is a debt service ratio?

It is the share of your gross income that goes to debt payments. Gross debt service (GDS) counts housing costs; total debt service (TDS) adds every other debt. On insured mortgages the limits are 39% and 44%, calculated at the stress-test rate of the greater of the contract rate plus 2% and 5.25%. Work out your own ratios →

Which mortgage terms are specific to Nova Scotia?

The ones buyers meet most are deed transfer tax (1.0% to 1.5% of the price, set by each of 49 municipalities), the Capped Assessment Program, the Down Payment Assistance Program and the First-time Homebuyers Program, the estoppel certificate on a condo, and parcel migration under the Land Registration Act. This glossary marks 21 Nova Scotia terms. Nova Scotia mortgage rules, answered →

Still unsure? Ask me directly.

If your question isn't here, your situation is probably specific. Fifteen minutes on the phone beats reading another page, and nothing is pulled on your credit.

Book a 15-minute call

(902) 298-0218 · Monday to Friday, 9:00 am to 5:00 pm Atlantic

Found a word in your paperwork that isn’t here?

A phone number or an email address — whichever you would rather be reached on. Both is fine.

Your details go straight to Riley and are used only to answer this request. No credit check at this stage. See the privacy policy.

That didn’t send.

Something went wrong on our side and your message did not go through. Please call or email instead; the details are below.

Call (902) 298-0218 or email [email protected].

Ready when you are.

Fifteen minutes on the phone tells you what you qualify for, what closing will cost in your municipality, and whether a broker or your own bank is the better route. No fee, no credit check, no obligation.

Book a 15-minute call See what I qualify for

(902) 298-0218 · Monday to Friday, 9:00 am to 5:00 pm Atlantic