
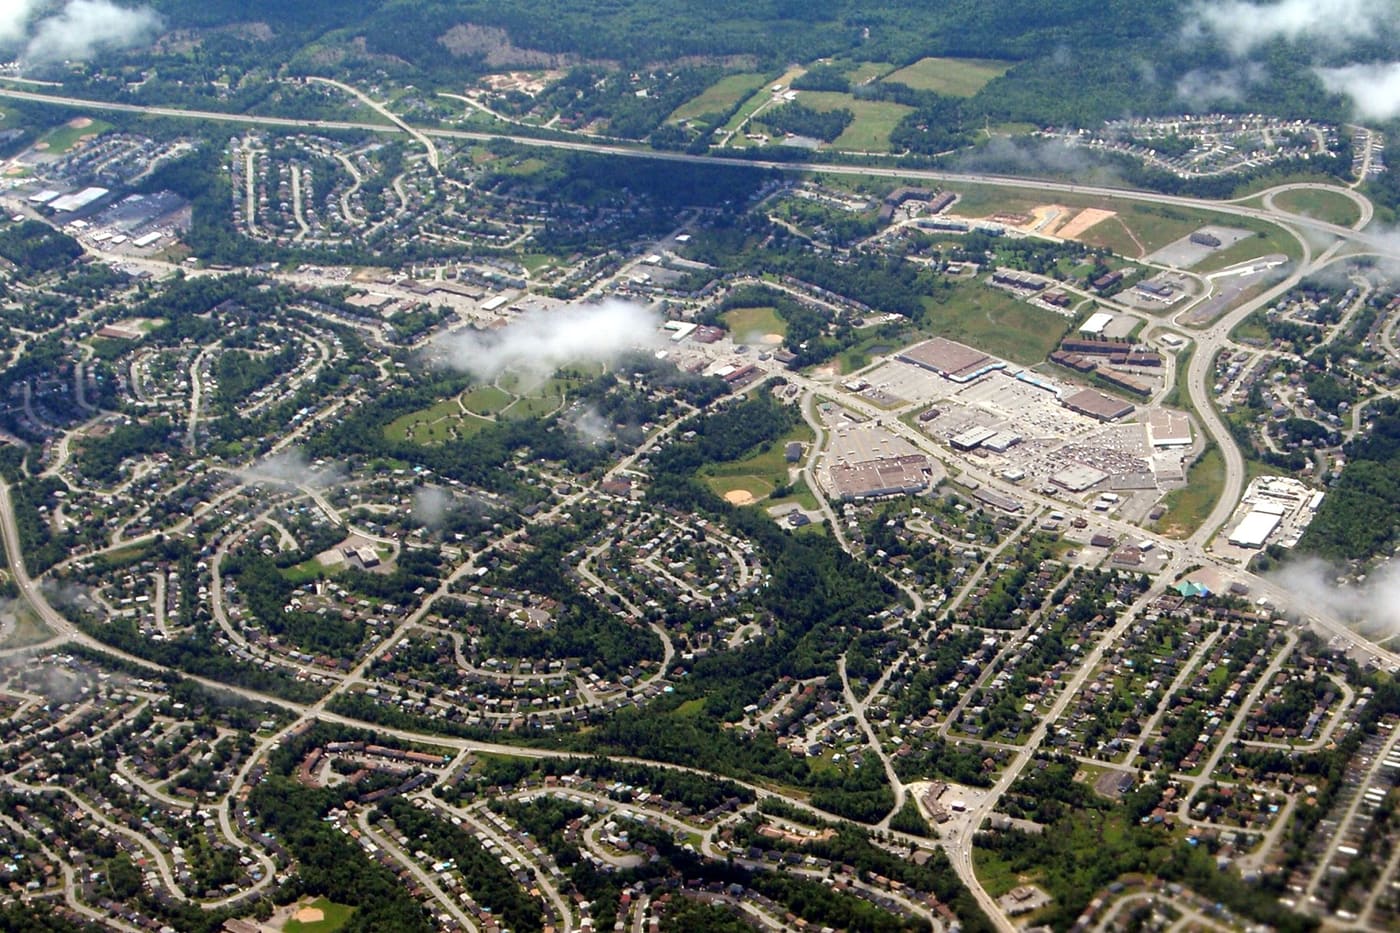
Lower Sackville
Lower Sackville: $38,000 of debt rolled into a refinance
Should I roll $38,000 of credit cards and a line of credit into my mortgage at renewal?
Should I roll $38,000 of credit cards and a line of credit into my mortgage at renewal?
Often, if you keep paying what you pay now. Rolling $38,000 into a $303,000 refinance at renewal drops the monthly outlay from $2,674 to $1,669, and total debt service from 48% to 35%. Spread over 25 years the debt costs about $24,779 in interest at the example rate; prepaid at the old $1,010, it clears in about 41 months.
Illustrative example
The situation
- Location
- Lower Sackville, Halifax Regional Municipality
- Borrower
- A single homeowner five years into a 25-year mortgage, at the end of her first term
- Income
- $88,000, salaried, a provincial government job
- Credit
- Low 700s; $22,000 across two cards near their limits and a $16,000 line of credit
- Original price
- $340,000
- Mortgage
- $303,000
- Payment at 4.45%
- $1,669 a month
The challenge
Two cards at 19.99% on her statements, an illustrative assumption, carried $22,000 at a $660 minimum, and a $16,000 line of credit took $350 more. The balances had not moved in two years. The renewal was three months out, and on those debts her total debt service ran 48%, above the 44% any lender allows.
What the lender looked at
- The 80% ceiling: $384,000 on a $480,000 appraisal, so the $303,000 new balance sits at 63% loan-to-value with room to spare.
- Timed at renewal, so no prepayment charge; three months earlier, a fixed term would have cost the greater of an amount equal to three months’ interest on what you still owe and the interest rate differential.
- Qualified at 6.45% on the full $303,000: $2,020 a month, 35% total debt service once the cards and line are paid out at closing as a condition of funding.
- A refinance taking equity out cannot be insured, so it is a conventional mortgage; the amortization can be reset to 25 years or held at the remaining 20.
- Card utilisation near the limit had been dragging the score; paying to zero from the proceeds is the lender’s condition and the borrower’s benefit.
What was done
The refinance was set at $303,000, with the cards and the line paid directly from the proceeds by the lawyer. Two versions were shown. At 25 years the payment is $1,669. At the remaining 20 years it is $1,902, and keeping the old $2,674 going, with the difference as a prepayment, clears the $38,000 in about 41 months.
The outcome
Illustrative outcome: a $303,000 mortgage at 4.45% (chartered-bank prime rate, Bank of Canada, 2026-09-16) over 25 years is $1,669 a month, $1,005 less than the $2,674 she was paying, with total debt service at 35%. Left unprepaid, the $38,000 costs about $24,779 in interest over the 25 years; prepaid at the old rate of payment, a fraction of that. No deed transfer tax, since nothing changes hands.
$1,005 a month freed up
Monthly cash flow freed by rolling $38,000 of cards and a line of credit into the refinance at renewal
- 48% → 35%Total debt service, before and afterAt the stress-test rate, against the 44% ceiling
- $303,000Refinance at renewal63% of the $480,000 appraisal, under the $384,000 ceiling
- $24,779Interest if carried 25 yearsOn the $38,000, at the example rate, if never prepaid
- 41 monthsTo clear with prepaymentsKeeping the old $1,010 a month going against the mortgage
Illustrative example; the 19.99% card rate is a scenario assumption, not a published figure. Mortgage figures at the chartered-bank prime rate, Bank of Canada, 2026-09-16; refinance ceiling: Financial Consumer Agency of Canada; qualifying under OSFI’s rule.
Go deeper
The detail, if you want it
What to take from it
- The saving is cash flow, not cost, unless you prepay. Most Nova Scotia mortgages allow 15–20% of the original balance a year without penalty; $1,010 a month is well inside that.
- Do it at renewal if you can wait; the same consolidation three months earlier carries a prepayment charge.
- Keep the cards open at zero. Closing them drops your available credit and can lower the score the payout just improved.
- Cards refilled within two years leave you with the mortgage and the cards. If that is likely, the right referral is a licensed insolvency trustee, not a refinance.
How the figures were computed
This is an illustrative example. The people, the property and the outcome are not real; the rules and the arithmetic are. Prices are the August 2026 regional averages from Nova Scotia Association of REALTORS® / CREA monthly statistics, or a stated example price; the deed transfer tax is the municipal rate on the provincial schedule; premiums are CMHC’s published schedule; qualifying uses OSFI’s rule. The contract rate is named in the outcome with its source. Legal, recording and title figures are typical ranges, not quotes.
- www.canada.ca: https://www.canada.ca/en/financial-consumer-agency/services/mortgages/borrow-home-equity.html
- www.osfi-bsif.gc.ca: https://www.osfi-bsif.gc.ca/en/supervision/financial-institutions/banks/minimum-qualifying-rate-uninsured-mortgages
- www.cmhc-schl.gc.ca: https://www.cmhc-schl.gc.ca/professionals/project-funding-and-mortgage-financing/mortgage-loan-insurance/mortgage-loan-insurance-homeownership-programs/cmhc-purchase
- www.canada.ca: https://www.canada.ca/en/financial-consumer-agency/services/mortgages/reduce-prepayment-penalties.html
- creastats.crea.ca: https://creastats.crea.ca/board/nsar/
How it works
From first call to keys, in four steps
-
A 15-minute call
You say what you’re trying to do and roughly what you earn.
Riley tell you the price a lender will support, the cash you need to close, and what to fix first.
-
Documents and pre-approval
You send the short list through a secure upload link.
Riley package the file and come back with a pre-approval letter and a rate held 90 to 120 days.
-
Lenders, side by side
You read the comparison and pick.
Riley place one application with banks, credit unions and monolines, and show you every answer.
-
Approval, lawyer, keys
You sign with your own local lawyer.
Riley hold the lender, appraiser and lawyer to the closing date.
Why a broker
Licensed, independent, paid by the lender
- Licensed in Nova Scotia Associate broker 3001134, verifiable on the provincial register
- $0 broker fee On a standard residential mortgage the lender pays, not you
- Banks, credit unions, monolines One application, one credit check, placed with the lender that reads your file best
- Every part of the province Bedford office, remote process: Yarmouth to Sydney, the same four steps
Questions people ask
Why is total debt service tested at 6.45% when the mortgage rate is 4.45%?
Every federally regulated lender qualifies an uninsured mortgage at the greater of the contract rate plus 2% and 5.25%. The card and line payments count at their actual minimums; the mortgage counts at $2,020 rather than $1,669. That is why the file failed before at 48% and passes after at 35%.
What if the debts had been $80,000 instead of $38,000?
$345,000 would still sit under the $384,000 ceiling, so the equity is there. The question becomes whether the ratios clear and whether the pattern repeats; beyond what 80% of the home can absorb, a refinance spends the equity that protects you and delays the problem a year.
Does consolidating hurt my credit score?
Short term, usually the opposite: revolving balances paid to zero drop your utilisation, roughly 30% of a typical score, and the effect shows within a cycle or two. The new mortgage inquiry costs a few points for a few months. The risk is behavioural, not arithmetical.
Still unsure? Ask me directly.
If your question isn't here, your situation is probably specific. Fifteen minutes on the phone beats reading another page, and nothing is pulled on your credit.
(902) 298-0218 · Monday to Friday, 9:00 am to 5:00 pm Atlantic
Sent. Thank you.
Your details went straight to Riley. He replies within one business day, usually sooner, by phone or email.
Need it faster? Call (902) 298-0218, Monday to Friday, 9:00 am to 5:00 pm Atlantic.
Your numbers, not the regional average
Send the listing or the statement and a rough income. You get back the same worked arithmetic on your actual figures, in writing, within a business day, at no fee.
(902) 298-0218 · Monday to Friday, 9:00 am to 5:00 pm Atlantic