
Annapolis Valley
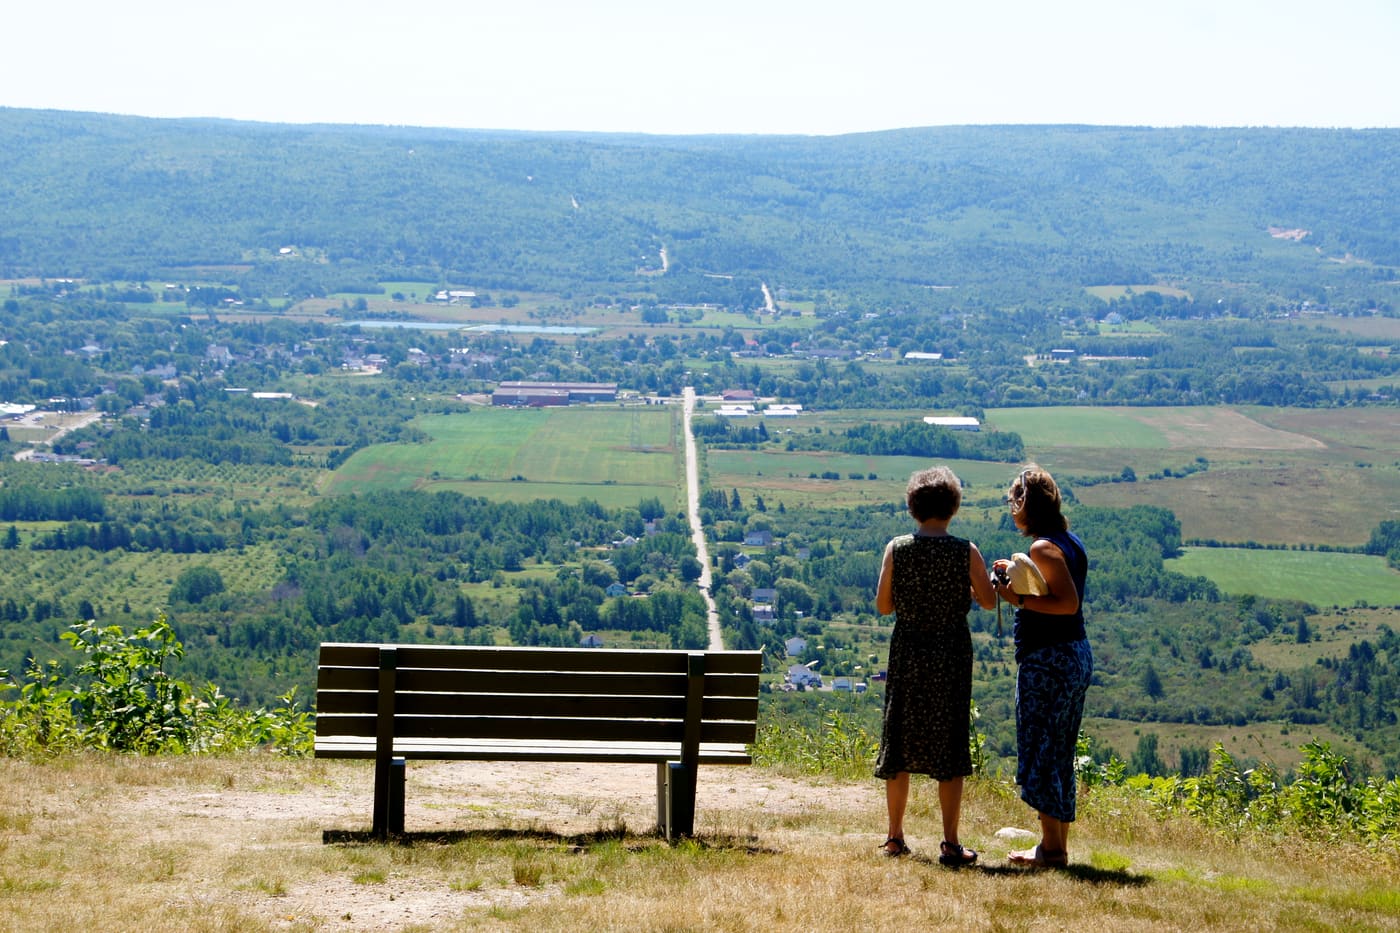
Outside Kentville: a drilled well, septic and an oil tank
What does a lender need before it will finance a rural home on a well and septic near Kentville?
What does a lender need before it will finance a rural home on a well and septic near Kentville?
Proof the water is potable and the septic works, in writing, before the advance. On a $385,000 house outside Kentville with $38,500 down, the lender asked for a bacteria test, a full chemistry panel for arsenic and uranium, a septic inspection and an insurance binder that accepted the oil tank. The financing condition ran 10 business days, not five.
Illustrative example
The situation
- Location
- Kings County, west of Kentville
- Borrower
- A couple moving from a Kentville apartment, both salaried, one at the hospital
- Income
- $105,000 household, two T4s
- Credit
- Both mid-700s; a $290 car payment
- Purchase price
- $385,000
- Down payment
- $38,500
- Mortgage
- $357,242
- Payment at 4.45%
- $1,967 a month
- Down payment $38,500
- Mortgage $357,242
Kings County, west of Kentville; Annapolis Valley region, where the August 2026 NSAR average was $394,019.
The challenge
A three-bedroom house on two acres off Highway 1 west of Kentville, with a drilled well, a septic field installed in the 1990s, and an oil furnace with a tank in the basement. The buyers had a five-business-day financing condition in the draft offer, which was not enough time for a water sample to come back from the lab.
What the lender looked at
- Potability: a bacteria result from an accredited lab showing no E. coli or total coliforms, dated within the lender’s window. Nova Scotia names arsenic and uranium, which Nova Scotia names as prevalent in the province and a health risk; neither shows on a bacteria test, so the full panel was ordered too.
- Septic: an inspection by a licensed installer or inspector, with a tank pump-out and a look at the field, since the appraiser notes the system but does not test it.
- The oil tank: the province sets no age limit and insurers do not publish theirs, so no number applies. The metal tag or label on the tank carries the manufacturing standard and the year of manufacture — it should never be painted over, and the insurer decides. No binder naming the lender as mortgagee, no advance.
- Two acres: some lenders reduce loan-to-value on large acreage; at 90% on an insured file, the appraisal had to support the full $385,000 on the house and the first acre or two.
- Qualified at 6.45%: $2,382 a month, 33% gross debt service on $105,000 with property tax and heat.
What was done
The offer was rewritten with a 10-business-day financing condition and a separate condition for the water, septic and insurance. Samples went to the lab the day the offer was accepted, the septic inspector came the same week, and the insurer was given the tank’s tag before the binder was requested. Everything was in the lender’s hands with two days to spare.
The outcome
Illustrative outcome: a $357,242 insured mortgage over 25 years at 4.45% (chartered-bank prime rate, Bank of Canada, 2026-09-16) is about $1,967 a month, qualified at $2,382. Cash on closing: $44,275 for the down payment and Kings County deed transfer tax, plus legal fees and the lab and inspection invoices, which the buyers paid directly.
Go deeper
The detail, if you want it
What to take from it
- Write the financing condition for the slowest item, which on a rural property is the water sample, not the appraisal.
- Order the full chemistry panel while you still have a condition. A treatment system is a negotiating point before closing and your cost after.
- Read the tank tag yourself and photograph it; an unreadable or painted-over tag is the most common reason a binder is refused.
- Ask the seller for the last well test and any septic pump-out receipt; many rural sellers have both because their own insurer asked.
How the figures were computed
This is an illustrative example. The people, the property and the outcome are not real; the rules and the arithmetic are. Prices are the August 2026 regional averages from Nova Scotia Association of REALTORS® / CREA monthly statistics, or a stated example price; the deed transfer tax is the municipal rate on the provincial schedule; premiums are CMHC’s published schedule; qualifying uses OSFI’s rule. The contract rate is named in the outcome with its source. Legal, recording and title figures are typical ranges, not quotes.
- novascotia.ca: https://novascotia.ca/well-water-testing/
- novascotia.ca: https://novascotia.ca/nse/water/docs/wellwaterbookletEnglish.pdf
- novascotia.ca: https://novascotia.ca/lae/fuelsafety/petroleum-domestic/
- www.cmhc-schl.gc.ca: https://www.cmhc-schl.gc.ca/consumers/home-buying/mortgage-loan-insurance-for-consumers/cmhc-mortgage-loan-insurance-cost
- novascotia.ca: https://novascotia.ca/sns/pdf/ans-property-dtt-rates.pdf
- www.osfi-bsif.gc.ca: https://www.osfi-bsif.gc.ca/en/supervision/financial-institutions/banks/minimum-qualifying-rate-uninsured-mortgages
- creastats.crea.ca: https://creastats.crea.ca/board/nsar/
How it works
From first call to keys, in four steps
-
A 15-minute call
You say what you’re trying to do and roughly what you earn.
Riley tell you the price a lender will support, the cash you need to close, and what to fix first.
-
Documents and pre-approval
You send the short list through a secure upload link.
Riley package the file and come back with a pre-approval letter and a rate held 90 to 120 days.
-
Lenders, side by side
You read the comparison and pick.
Riley place one application with banks, credit unions and monolines, and show you every answer.
-
Approval, lawyer, keys
You sign with your own local lawyer.
Riley hold the lender, appraiser and lawyer to the closing date.
Why a broker
Licensed, independent, paid by the lender
- Licensed in Nova Scotia Associate broker 3001134, verifiable on the provincial register
- $0 broker fee On a standard residential mortgage the lender pays, not you
- Banks, credit unions, monolines One application, one credit check, placed with the lender that reads your file best
- Every part of the province Bedford office, remote process: Yarmouth to Sydney, the same four steps
Questions people ask
What if the water test had failed?
A bacteria failure is usually fixed by shocking the well and retesting, a matter of days. Arsenic or uranium above the guideline means a treatment system, negotiated as a price reduction or a seller repair while the condition is open. Lead above 0.005 and manganese above 0.12 milligrams per litre are the other two figures to look for on the report.
Does the oil tank have to be replaced before closing?
Only if the insurer says so; Nova Scotia sets no age limit, and installation must be by a trained and licensed oil burner technician to CSA B139, Installation Code for Oil-Burning Equipment, and the National Fire Code of Canada. In this example the tag showed a tank 9 years old and the insurer accepted it. A refused tank means a replacement quote in the negotiation before the condition expires.
Why did the 10% down payment still need CMHC insurance?
Anything under 20% down is a high-ratio mortgage and must be insured. At 90% loan-to-value the premium is 3.1% of the $346,500 borrowed, $10,742, added to the mortgage rather than paid in cash. Nova Scotia charges no provincial sales tax on the premium.
Still unsure? Ask me directly.
If your question isn't here, your situation is probably specific. Fifteen minutes on the phone beats reading another page, and nothing is pulled on your credit.
(902) 298-0218 · Monday to Friday, 9:00 am to 5:00 pm Atlantic
Sent. Thank you.
Your details went straight to Riley. He replies within one business day, usually sooner, by phone or email.
Need it faster? Call (902) 298-0218, Monday to Friday, 9:00 am to 5:00 pm Atlantic.
Your numbers, not the regional average
Send the listing or the statement and a rough income. You get back the same worked arithmetic on your actual figures, in writing, within a business day, at no fee.
(902) 298-0218 · Monday to Friday, 9:00 am to 5:00 pm Atlantic